Navigating the Shifting Sands: A Deep Dive into the 2026 Housing Market Forecast
The real estate landscape is perpetually in motion, influenced by a complex interplay of economic, social, and demographic factors. As we cast our gaze towards the future, specifically the 2026 housing market, industry experts and economists are beginning to paint a clearer picture of what lies ahead. One of the most significant projections currently circulating is the anticipation of a potential 7% price adjustment in key US regions. This isn’t merely a statistic; it’s a signal that could reshape investment strategies, homeownership aspirations, and the overall economic trajectory for millions.
Understanding the nuances of this forecast requires a comprehensive analysis of the forces at play. Is this adjustment a cause for alarm, or an opportunity for a more balanced market? This article will dissect the primary drivers behind the predicted 7% price shift, examine the regions most likely to be affected, and offer actionable insights for various stakeholders in the real estate ecosystem. From interest rate fluctuations and supply-demand dynamics to demographic shifts and regulatory changes, we’ll explore every facet that contributes to the evolving 2026 housing market outlook.
Unpacking the 7% Price Adjustment: What Does it Mean?
A 7% price adjustment in the 2026 housing market might sound substantial, but it’s crucial to contextualize this figure. It doesn’t necessarily imply a nationwide crash but rather a recalibration in specific, often overheated, markets. Historically, housing markets operate in cycles, and periods of rapid appreciation are often followed by plateaus or modest corrections. The last few years have seen unprecedented growth in home values, fueled by low interest rates, remote work migration, and limited inventory.
This projected adjustment suggests a return to more sustainable growth patterns, or even a slight cooling, as market conditions normalize. For potential homebuyers, this could translate into increased affordability and less intense bidding wars. For sellers, it might mean adjusting expectations regarding sale prices and market timelines. Investors, too, will need to adapt their strategies, potentially focusing on markets with stronger underlying fundamentals or opportunities for value-add propositions. The 7% figure serves as a benchmark, indicating a significant, but not catastrophic, shift in market equilibrium for the 2026 housing market.
Key Drivers Behind the 2026 Housing Market Forecast
Several critical factors are converging to shape the 2026 housing market. Understanding these drivers is essential for anyone looking to make informed decisions in the coming years.
Interest Rate Trajectories and Their Impact
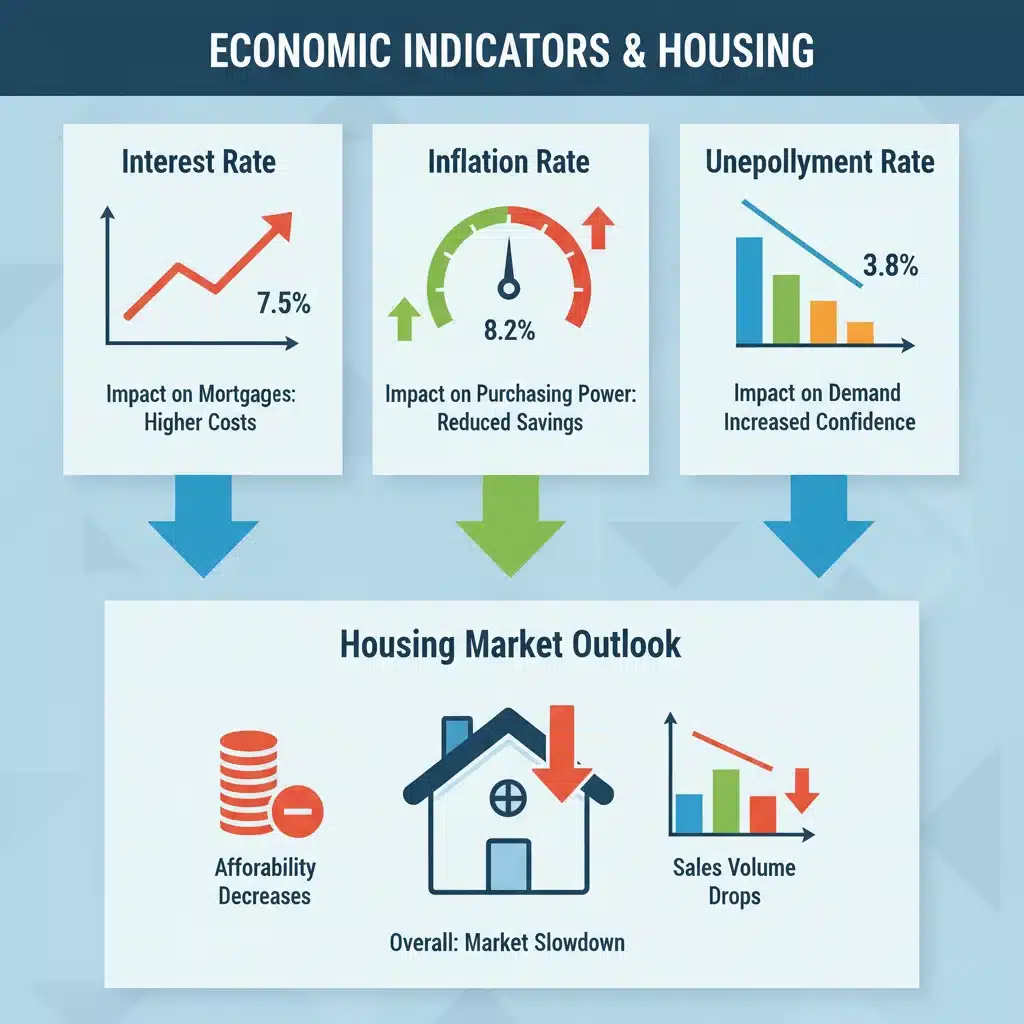
Interest rates are arguably the most influential factor in housing affordability and demand. The Federal Reserve’s monetary policy decisions directly affect mortgage rates. If inflation continues to moderate, the Fed might have room to hold rates steady or even implement modest cuts, which could offer some relief to buyers. However, if inflationary pressures persist, higher rates could remain, further dampening demand and contributing to price adjustments in the 2026 housing market.
Higher interest rates increase the cost of borrowing, making monthly mortgage payments more expensive even if home prices remain constant. This reduces purchasing power for many prospective buyers, leading to a natural cooling of demand. Conversely, a sustained period of lower rates could reignite buyer interest, though the current economic climate suggests that significantly lower rates might not be on the immediate horizon for the 2026 housing market.
Supply and Demand Dynamics
The fundamental economic principles of supply and demand remain paramount. For years, many US housing markets have grappled with a significant shortage of available homes, a key contributor to escalating prices. While new construction has picked up in some areas, it has not been enough to fully address the deficit.
In 2026, we could see a more balanced market emerge. Increased inventory, whether from new builds finally catching up, or from existing homeowners choosing to sell as rates stabilize, would alleviate some of the upward pressure on prices. Conversely, if supply remains constrained, even with higher rates, price corrections might be less pronounced. The interplay between these forces will be a defining characteristic of the 2026 housing market.
Demographic Shifts and Migration Patterns
Demographics play a long game in real estate. The millennial generation, now in their prime home-buying years, continues to exert significant influence. Their purchasing power and preferences will heavily shape demand. Gen Z is also starting to enter the market, albeit at a slower pace. Additionally, internal migration patterns, driven by factors like remote work flexibility, affordability, and climate concerns, will continue to impact regional markets differently.
Areas that have seen an influx of new residents in recent years due to remote work opportunities might experience a greater correction if those trends slow or reverse. Conversely, regions with strong job growth and attractive amenities could continue to see stable or even appreciating values, even within a broader market adjustment. These shifts are crucial for understanding the localized impacts within the overall 2026 housing market.
Economic Health and Inflation
The broader economic environment, including GDP growth, employment rates, and inflation, directly influences consumer confidence and financial capacity. A robust economy with stable employment typically supports a healthy housing market. However, persistent inflation can erode purchasing power and make homeownership less attainable, even for those with secure jobs.
If the economy enters a period of slower growth or a mild recession, it could further contribute to the predicted price adjustment. Conversely, a ‘soft landing’ for the economy, where inflation is tamed without a significant downturn, could lead to a more gradual and less severe market correction. Monitoring these macroeconomic indicators will be vital for anticipating movements in the 2026 housing market.
Which Key US Regions Are Most Susceptible to a 7% Price Adjustment?
While a national average of a 7% price adjustment provides a general outlook for the 2026 housing market, the reality on the ground will be highly localized. Not all regions will experience the same degree of change. Typically, markets that saw the most aggressive price appreciation in recent years, often driven by speculative buying or significant in-migration, are more vulnerable to corrections.
Overheated Sun Belt Markets
Many Sun Belt cities, particularly in states like Florida, Arizona, Texas, and parts of the Carolinas, experienced explosive growth during the pandemic. Low taxes, warmer climates, and newfound remote work flexibility attracted a flood of new residents, driving prices sky-high. Markets such as Boise, Phoenix, Austin, and parts of Florida’s Gulf Coast could see more significant adjustments as demand normalizes and affordability becomes a greater concern. The rapid appreciation in these areas makes them prime candidates for a corrective phase in the 2026 housing market.
Coastal Tech Hubs with High Valuations
While not experiencing the same recent boom as the Sun Belt, traditional high-cost coastal tech hubs like parts of California (e.g., San Francisco Bay Area, Los Angeles) and the Pacific Northwest (e.g., Seattle) have always operated at elevated price points. If the tech sector faces further layoffs or a slowdown, and hybrid work models reduce the necessity of living directly in these expensive urban cores, these markets could also see price adjustments. The sheer cost of entry in these areas makes them sensitive to shifts in economic conditions and buyer sentiment, influencing their performance in the 2026 housing market.
Suburban Areas That Saw Pandemic-Fueled Exoduses
Many suburban and exurban areas surrounding major metropolitan centers saw a surge in demand as people sought more space during the pandemic. While some of this demand might be sustained, others might experience a cooling as urban centers regain their appeal and commuting patterns stabilize. Regions that saw rapid, unsustainable growth driven by temporary factors might be more exposed to a price correction in the 2026 housing market.
Implications for Various Stakeholders
A 7% price adjustment in the 2026 housing market has different implications for various participants.
For Homeowners
Existing homeowners, especially those who purchased or refinanced in recent years, generally have significant equity. A 7% adjustment might reduce their paper gains but is unlikely to put them underwater unless they bought at the absolute peak with minimal down payment. For those looking to sell, it might mean a slightly longer time on the market or a need to adjust their asking price to reflect current conditions. It emphasizes the importance of maintaining property value through upkeep and smart renovations. Understanding the local dynamics of the 2026 housing market will be key.
For Potential Homebuyers
This forecast could be welcome news for prospective buyers. A price adjustment, coupled with potentially stable or slightly lower interest rates, could improve affordability and reduce competition. It might allow buyers more time to make decisions, conduct thorough inspections, and negotiate better terms. However, it’s crucial to remember that a 7% adjustment doesn’t mean homes will be ‘cheap’; it simply means they might be less expensive than their peak. Due diligence and financial preparedness remain paramount when entering the 2026 housing market.
For Real Estate Investors
Investors will need to be strategic. A market correction can uncover opportunities for those with capital and a long-term perspective. Distressed properties, areas with strong rental demand, or markets poised for future growth despite a temporary dip could become attractive. However, speculative investing in highly volatile markets could become riskier. Diversification and a thorough understanding of local market fundamentals will be more important than ever for investors navigating the 2026 housing market.
For Real Estate Professionals
Agents, brokers, and lenders will need to adapt their strategies to a more balanced or even buyer-favored market. Stronger negotiation skills, realistic pricing strategies, and an emphasis on client education will be critical. Building long-term relationships and providing exceptional service will differentiate successful professionals in the 2026 housing market.
Mitigating Risks and Seizing Opportunities in the 2026 Housing Market
Regardless of your role in the real estate market, proactive planning and informed decision-making are crucial. The projected 7% price adjustment in the 2026 housing market is a forecast, not a guarantee, but it provides a valuable framework for preparation.
For Homeowners: Protecting Your Investment
- Assess Your Equity: Understand your current equity position. This provides a buffer against potential price dips.
- Maintain Your Home: Regular maintenance and strategic upgrades can help preserve or even enhance your home’s value, making it more resilient in a softer market.
- Monitor Local Trends: Keep an eye on sales data, inventory levels, and economic indicators in your specific neighborhood or city.
- Consider Refinancing: If interest rates drop, evaluate whether refinancing could improve your financial position or reduce monthly payments.
For Buyers: Strategic Entry
- Strengthen Your Finances: Save for a larger down payment, improve your credit score, and get pre-approved for a mortgage to position yourself as a strong buyer.
- Research Thoroughly: Identify markets with strong fundamentals, good job growth, and sustainable population trends rather than chasing overheated areas.
- Be Patient and Prepared: The 2026 housing market might offer more negotiation room. Don’t rush into a purchase; be ready to act when the right opportunity arises.
- Work with a Knowledgeable Agent: A local expert can provide invaluable insights into micro-market conditions and help you navigate negotiations.
For Investors: Identifying Value
- Focus on Cash Flow: In a correcting market, properties with strong rental income potential become even more attractive.
- Look for Undervalued Assets: Opportunities might arise to acquire properties below their intrinsic value, especially in markets experiencing a more significant adjustment.
- Diversify Your Portfolio: Don’t put all your eggs in one geographic basket. Consider investing in different market types or property classes.
- Understand Local Regulations: Be aware of landlord-tenant laws, zoning changes, and other regulations that could impact your investment strategy. The 2026 housing market will reward informed investors.
The Role of Government Policies and Global Events
Beyond the immediate economic indicators, government policies and unforeseen global events can also significantly sway the 2026 housing market. Housing policy, including zoning reforms, affordable housing initiatives, and first-time homebuyer programs, can influence supply and demand dynamics. Changes in tax laws related to real estate can also impact investor sentiment and homeowner decisions.
Globally, geopolitical stability, trade relations, and international economic performance can have ripple effects on the US economy, and by extension, its housing market. For instance, a global economic slowdown could reduce foreign investment in US real estate or impact the overall economic confidence that underpins housing demand. While these factors are harder to predict, their potential influence on the 2026 housing market cannot be overlooked.
Historical Context: Lessons from Past Adjustments
Understanding past housing market cycles provides valuable perspective. The 2008 financial crisis, while an extreme example, taught us about the dangers of lax lending standards and speculative bubbles. More recently, the brief but sharp downturn in some markets during the early days of the pandemic highlighted the market’s resilience and capacity for rapid recovery under certain conditions.
A 7% price adjustment, in historical context, is a relatively modest correction compared to more severe downturns. It suggests a market that is recalibrating rather than collapsing. This historical perspective can help temper both excessive optimism and undue pessimism, fostering a more balanced approach to planning for the 2026 housing market.
Conclusion: A Balanced Outlook for the 2026 Housing Market
The forecast of a 7% price adjustment in key US regions for the 2026 housing market signals a period of transition and normalization. This is not necessarily a cause for alarm but rather an indication that the market is seeking a more sustainable equilibrium after several years of extraordinary growth. While some regions may experience more pronounced shifts, others might remain stable or continue to see modest appreciation.
For all participants, the key to navigating the 2026 housing market successfully will be adaptability, informed decision-making, and a keen awareness of local market conditions. Homeowners should focus on maintaining their investments, buyers should prepare financially and strategically, and investors should seek value and long-term potential. By understanding the underlying drivers and preparing for various scenarios, individuals can position themselves to thrive in the evolving real estate landscape of 2026 and beyond.
The future of the housing market is never certain, but by staying informed and agile, we can transform potential challenges into opportunities for growth and stability. The 2026 housing market will undoubtedly present its unique set of circumstances, and those who are best prepared will be best positioned to succeed.