US Sanctions 2026: Global Trade Shift Explained
US Sanctions 2026: A 15% Shift in Global Trade Flows Explained
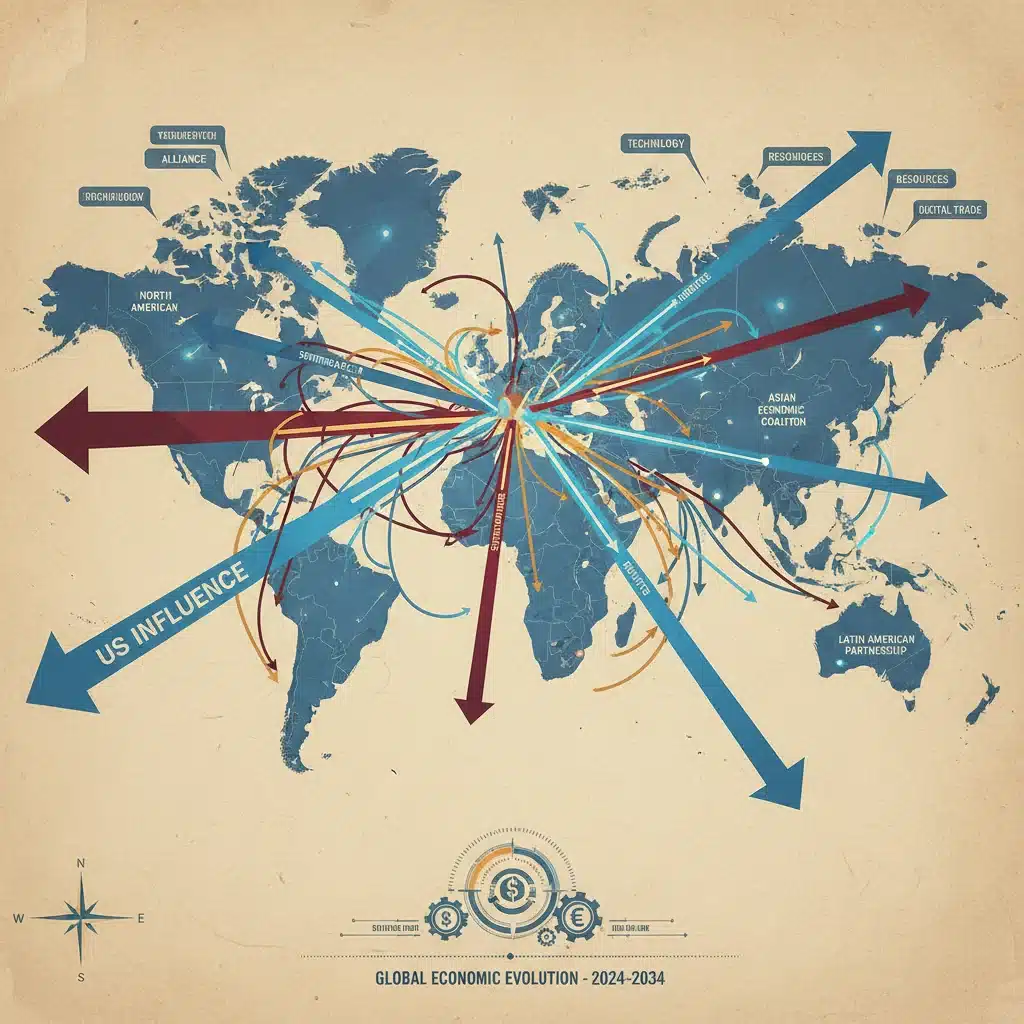
The global economic landscape is a dynamic tapestry, constantly reshaped by geopolitical forces, technological advancements, and evolving policy frameworks. Among these forces, the imposition of sanctions by major economic powers stands out as a particularly potent instrument capable of redrawing the lines of international commerce. As we approach 2026, the anticipated impact of US sanctions policies is projected to instigate a significant 15% shift in global trade flows, a monumental change that demands rigorous analysis and strategic foresight. This article delves deep into the mechanisms, implications, and potential reverberations of this impending transformation, providing a comprehensive overview for businesses, policymakers, and academics alike.
Understanding the full scope of this projected 15% shift requires an examination of the historical context of US sanctions, their evolving nature, and the specific sectors and regions most likely to bear the brunt – or reap the benefits – of these changes. The United States, as the world’s largest economy and a dominant player in international finance, wields considerable power through its ability to restrict access to its markets, financial systems, and technological resources. These restrictions, often aimed at achieving foreign policy objectives, can create ripple effects that extend far beyond the targeted entities or nations, influencing global supply chains, investment patterns, and diplomatic relations.
The year 2026 is not an arbitrary benchmark; it represents a horizon where current trends in international relations, technological competition, and economic decoupling are expected to mature into more concrete and measurable shifts. The 15% figure, while an estimation, underscores the magnitude of the disruption and realignment anticipated. This isn’t merely about rerouting a few shipments; it’s about fundamental changes in how goods, services, and capital move across borders, fostering new alliances, challenging existing hegemonies, and forcing nations to re-evaluate their economic dependencies.
This comprehensive exploration will cover the drivers behind the projected shift, the methodologies used to arrive at such a forecast, the specific economic sectors and geographical regions most susceptible to change, and the strategic responses being formulated by various international actors. We will also discuss the long-term implications for global governance, multilateral institutions, and the future of economic globalization. The aim is to provide clarity amidst complexity, offering actionable insights for navigating a world increasingly shaped by strategic economic statecraft.
The Evolving Landscape of US Sanctions Impact
The history of US sanctions is long and varied, dating back to the early days of the republic. However, the nature and application of these tools have evolved significantly, particularly in the post-Cold War era and even more so in the 21st century. Initially, sanctions were often broad and aimed at entire nations, but modern US sanctions have become increasingly sophisticated, targeting specific individuals, entities, or sectors within a country. This precision, while intended to minimize collateral damage, also allows for more strategic and impactful interventions that can have widespread consequences for global commerce.
Key drivers behind the continued reliance on US sanctions as a foreign policy instrument include national security concerns, human rights advocacy, counter-terrorism efforts, and responses to geopolitical aggression. The mechanisms through which these sanctions are implemented are diverse, ranging from asset freezes and travel bans to restrictions on financial transactions, export controls, and prohibitions on certain types of investment. The extraterritorial reach of US sanctions, often leveraging the dominance of the US dollar in international finance, means that even non-US entities engaging with sanctioned parties can face severe penalties, including exclusion from the US market.
The period leading up to 2026 is characterized by several trends that are likely to amplify the US Sanctions Impact on global trade. Firstly, heightened geopolitical tensions, particularly between major powers, are leading to increased weaponization of economic tools. Secondly, advancements in digital finance and supply chain tracking allow for more granular enforcement of sanctions, reducing avenues for circumvention. Thirdly, a growing emphasis on technological sovereignty and securing critical supply chains is prompting nations to diversify their trade partners, often in response to or anticipation of sanctions.
Moreover, the rise of secondary sanctions, which target entities doing business with sanctioned parties, further extends the reach and complexity of compliance. Companies worldwide are forced to conduct extensive due diligence to avoid inadvertently violating US regulations, leading to a phenomenon often termed ‘overcompliance’ where businesses err on the side of caution, even beyond the strict letter of the law. This creates a chilling effect on trade and investment with certain regions or sectors, contributing directly to the predicted 15% shift.
The cumulative effect of these factors is a global trading environment where political risk is increasingly intertwined with economic viability. Businesses must not only assess market demand and production costs but also navigate a labyrinth of evolving sanctions regimes. This necessitates a proactive approach to risk management, supply chain resilience, and strategic market diversification to mitigate the potential negative impacts and capitalize on new opportunities arising from the reordering of global trade flows.
Understanding the 15% Shift: Drivers and Methodology
The projection of a 15% shift in global trade flows by 2026 due to US Sanctions Impact is not a mere speculative figure; it is derived from a complex analysis of various economic models, historical precedents, and forward-looking assessments of geopolitical trends. This section unpacks the underlying drivers and the analytical methodology that underpins this significant forecast.
Economic Models and Data Analysis
Econometric models play a crucial role in predicting such large-scale shifts. These models incorporate a multitude of variables including GDP growth rates, trade elasticities, foreign direct investment flows, commodity prices, and, critically, the historical and projected impact of trade barriers like tariffs and sanctions. By analyzing past instances where sanctions were imposed or lifted, economists can calibrate the expected response of trade volumes and patterns.
- Gravity Models of Trade: These models predict bilateral trade flows based on the economic size of countries (GDP) and the distance between them, along with other factors like common language or colonial ties. Sanctions introduce a ‘negative’ factor, effectively increasing the ‘distance’ or cost of trade between sanctioned and sanctioning economies.
- Input-Output Analysis: This method examines the interdependencies between different sectors of an economy. Sanctions targeting a specific industry in one country can have cascading effects on upstream and downstream industries globally, altering demand for components, raw materials, and finished goods.
- Supply Chain Mapping: Modern analysis increasingly relies on detailed mapping of global supply chains to identify critical choke points and alternative routes. Disruptions caused by sanctions force companies to re-evaluate their sourcing and distribution networks, leading to measurable shifts in trade lanes.
Geopolitical Scenarios and Expert Consensus
Beyond quantitative models, the 15% figure also incorporates qualitative assessments from geopolitical analysts and trade experts. These experts evaluate various scenarios regarding future US foreign policy, the likelihood of new sanctions being imposed, and the responses of targeted and third-party nations. Factors considered include:
- US Domestic Political Climate: Changes in US administration or congressional priorities can significantly alter the direction and intensity of sanctions policy.
- International Alliances and Counter-Sanctions: The formation of new trade blocs or the imposition of retaliatory sanctions by other major economies can accelerate or mitigate the shift.
- Technological Decoupling: Efforts by nations to achieve self-sufficiency in critical technologies (e.g., semiconductors, AI) often driven by security concerns and the threat of sanctions, will inherently lead to a restructuring of technology trade flows.
Historical Precedents and Current Trends
While each sanctions regime is unique, historical data provides valuable insights. The impact of sanctions on countries like Iran, Russia, and Venezuela has demonstrated the capacity of such measures to significantly alter their trade relationships and economic structures. Extrapolating these observed effects to a broader global context, considering the increasing interconnectedness of economies, helps in projecting the aggregate 15% shift. Current trends, such as the diversification efforts by China and European nations to reduce reliance on single markets or suppliers, further support the notion of an ongoing, significant realignment.
The 15% figure represents an aggregate change, meaning that some sectors and regions will experience much larger shifts, while others may see minimal impact. It’s a net effect of both diversion (trade moving from sanctioned to unsanctioned partners) and reduction (overall decrease in certain types of trade due to increased costs or barriers). This complex interplay of forces ensures that the US Sanctions Impact is felt across the entire spectrum of global commerce.
Key Sectors and Regions Feeling the US Sanctions Impact
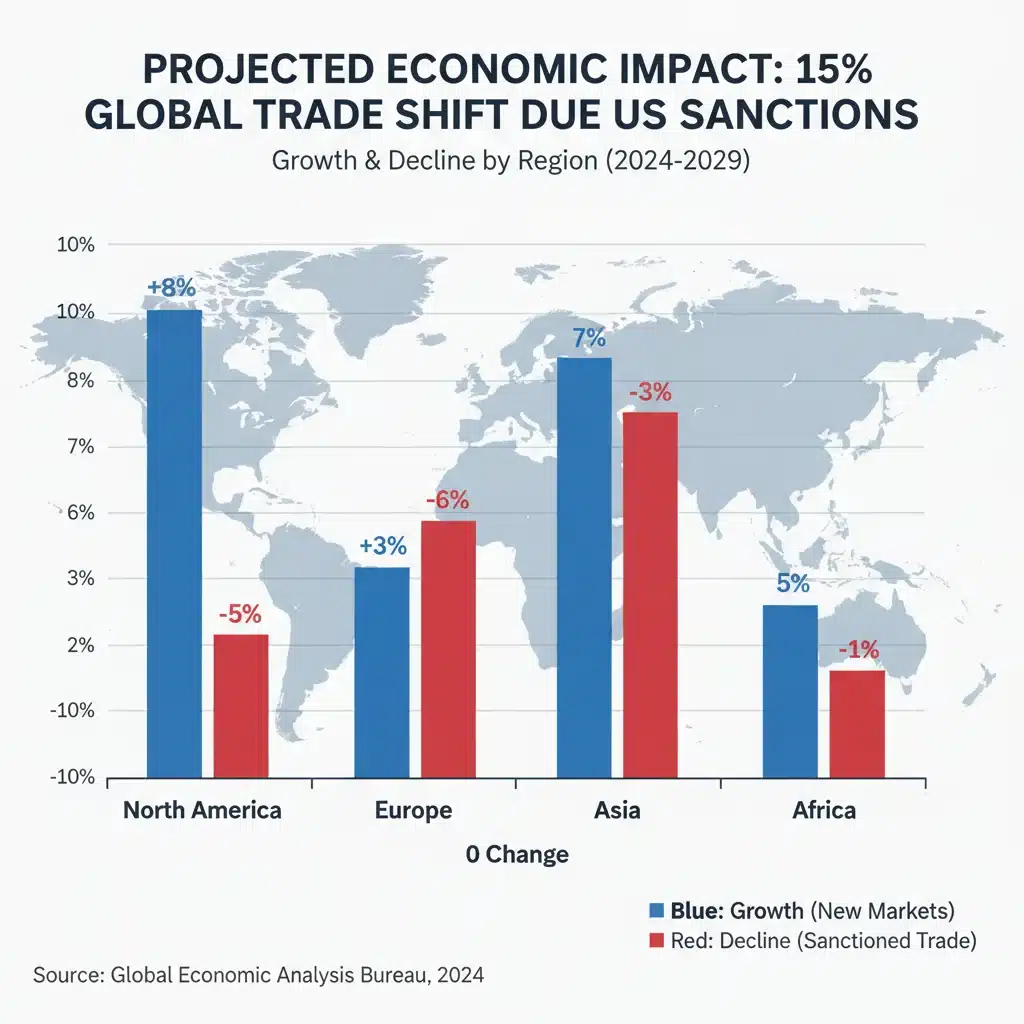
The projected 15% shift in global trade flows will not be uniformly distributed. Instead, certain economic sectors and geographical regions are expected to experience a disproportionately larger US Sanctions Impact. Identifying these areas is crucial for understanding the practical implications of the impending changes.
Sectors Most Affected
Several industries are particularly vulnerable to US sanctions due to their strategic importance, high technological content, or reliance on international financial systems:
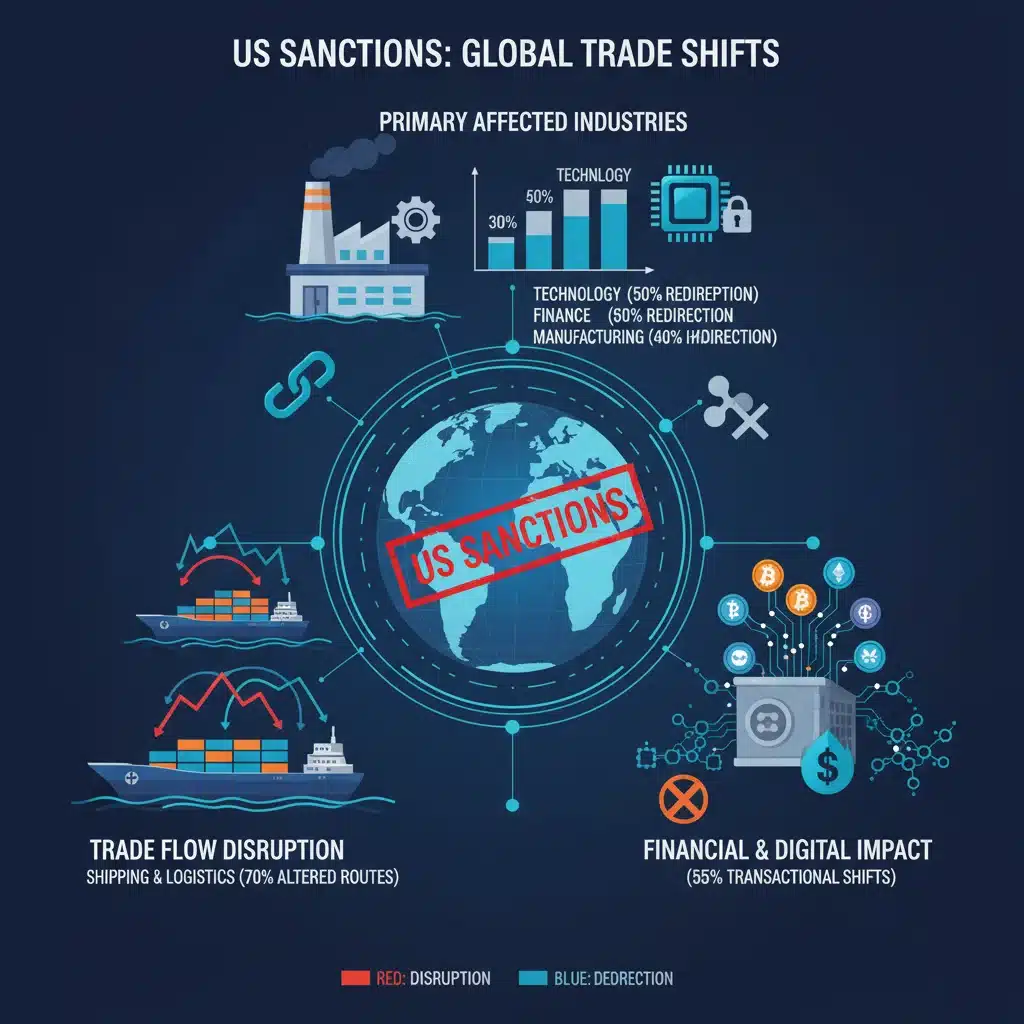
- Technology and High-Tech Manufacturing: This sector is a frequent target, especially regarding dual-use technologies (civilian and military applications). Sanctions on critical components like semiconductors, advanced machinery, and software can severely disrupt global supply chains, forcing nations to develop indigenous alternatives or seek new suppliers. This directly contributes to the 15% shift as trade routes for these vital goods are rerouted.
- Energy (Oil & Gas): As seen with countries like Iran and Russia, sanctions on energy exports or imports can dramatically alter global energy markets. This not only affects the sanctioned entities but also prompts major energy consumers to diversify their sources, leading to new long-term contracts and infrastructure investments in alternative regions.
- Financial Services: Given the centrality of the US dollar in international transactions, financial sanctions have a pervasive effect. Restrictions on banking, credit, and investment can isolate economies, making it difficult for businesses to conduct international trade. This encourages the development of alternative payment systems and non-dollar denominated trade, a significant component of the 15% shift.
- Defense and Aerospace: This sector is almost perennially subject to strict export controls and sanctions, and any new measures or expansions will further solidify existing trade blocs and limit cross-border collaboration to trusted partners.
- Luxury Goods and Consumer Electronics: While not as strategically critical, these sectors often face import/export restrictions as a means of economic pressure, impacting consumer markets and manufacturing hubs.
Regions Undergoing Significant Realignments
Geographically, the US Sanctions Impact will manifest differently across various continents and economic blocs:
- East Asia (China, South Korea, Japan): Given its deep integration into global supply chains and its pivotal role in high-tech manufacturing, East Asia will be at the epicenter of many of these shifts. China, in particular, is actively pursuing strategies to reduce its vulnerability to US sanctions, leading to increased intra-Asian trade and investment in domestic capabilities. South Korea and Japan, while US allies, will also need to carefully navigate their economic relationships to maintain stability.
- Europe (EU): European nations face a delicate balancing act. As significant trading partners with both the US and countries often targeted by sanctions, they must often choose between complying with US regulations and maintaining independent economic ties. This has spurred efforts within the EU to strengthen its own economic sovereignty and develop mechanisms to protect European companies from extraterritorial sanctions, contributing to a reorientation of some trade flows.
- Russia and CIS Countries: Already heavily sanctioned, these regions will likely see further deepening of trade ties with non-Western partners, primarily China and India, accelerating the pivot towards an ‘East-oriented’ trade architecture.
- Middle East and North Africa (MENA): Countries in this region, particularly those with significant energy resources or geopolitical sensitivities, are consistently affected. The search for new markets for their exports and alternative sources for imports will contribute to the global trade shifts.
- Latin America and Africa: While perhaps less directly targeted, these regions will feel the ripple effects as major powers adjust their trade strategies. They may become increasingly attractive as alternative sourcing or market destinations for countries seeking to diversify away from traditional partners affected by sanctions. This could lead to new investment and trade opportunities, even as existing relationships are strained.
The 15% shift represents a complex mosaic of re-routing, re-sourcing, and re-strategizing across these sectors and regions. Companies and governments that anticipate these changes and adapt proactively will be better positioned to navigate the evolving global trade environment.
Strategic Responses and Future Outlook
The projected 15% shift in global trade flows by 2026, driven by the expanding US Sanctions Impact, is not merely an economic forecast; it is a catalyst for strategic recalibration across governments and corporations worldwide. Understanding these responses and peering into the future outlook is essential for navigating the transformed global commercial landscape.
Governmental Responses: Diversification and De-risking
Nations are increasingly recognizing the imperative to build resilience against the weaponization of economic interdependence. This has led to several key governmental strategies:
- Supply Chain Resilience: Governments are investing in domestic production capabilities for critical goods (e.g., semiconductors, rare earths, pharmaceuticals) and encouraging companies to diversify their sourcing away from single points of failure, especially those vulnerable to sanctions. This ‘friend-shoring’ or ‘near-shoring’ trend aims to reduce reliance on potentially adversarial nations.
- Development of Alternative Payment Systems: To counter the dominance of the US dollar and the associated risk of financial sanctions, countries like China (with its CIPS system) and the EU (exploring INSTEX-like mechanisms) are working on alternative payment infrastructures. The increasing interest in central bank digital currencies (CBDCs) also plays into this strategy, potentially allowing for transactions outside traditional SWIFT channels.
- Strengthening Regional Trade Blocs: The formation and strengthening of regional trade agreements (e.g., RCEP, CPTPP) and economic partnerships (e.g., BRICS expansion) serve as a hedge against global disruptions. These blocs aim to foster intra-regional trade and reduce external dependencies.
- Legal and Diplomatic Countermeasures: Some nations are enacting ‘blocking statutes’ or similar legislation to protect their companies from the extraterritorial application of US sanctions. Diplomatic efforts are also underway to advocate for a more multilateral approach to sanctions, rather than unilateral impositions.
Corporate Strategies: Adaptation and Innovation
Businesses, faced with the realities of the US Sanctions Impact, are also evolving their strategies:
- Geographic Diversification: Companies are expanding their market presence and investment portfolios into new regions, particularly in emerging economies, to mitigate risks associated with over-reliance on specific markets that might be targeted by sanctions.
- Technological Independence: Firms are investing heavily in R&D to reduce their dependence on proprietary technologies from countries that might impose export controls. This includes developing in-house capabilities or partnering with companies from politically aligned nations.
- Enhanced Compliance and Due Diligence: The complexity of sanctions regimes necessitates robust compliance programs. Companies are investing in sophisticated software and expert personnel to ensure adherence to international regulations and avoid costly penalties.
- Agile Supply Chain Management: Building flexibility into supply chains, including maintaining buffer stocks, identifying alternative suppliers, and developing contingency plans, is becoming paramount. This allows businesses to pivot quickly in response to unforeseen sanctions.
Long-Term Implications and Future of Globalization
The 15% shift in global trade flows by 2026 points towards a more fragmented, yet potentially more resilient, global economy. While some argue it signals a retreat from globalization, others contend it’s merely a recalibration towards a ‘multi-polar’ or ‘de-globalized’ model where trade is more regionalized and less concentrated. Key implications include:
- Increased Regionalization: Trade within existing or newly formed regional blocs is likely to intensify, potentially at the expense of long-distance global trade routes.
- New Economic Power Centers: The shifts could accelerate the rise of new economic powerhouses, particularly in Asia, as they strengthen intra-regional ties and develop alternative trade and financial infrastructures.
- Innovation and Self-Sufficiency: The push for technological independence and supply chain resilience will drive significant innovation and investment in domestic industries in many countries.
- Challenges to Multilateralism: The unilateral nature of many sanctions poses ongoing challenges to the principles of multilateralism and the rules-based international order, potentially weakening institutions like the WTO.
- Inflationary Pressures: Re-routing supply chains, investing in less efficient domestic production, and duplicating technological capabilities can lead to increased costs, potentially contributing to inflationary pressures globally.
In conclusion, the US Sanctions Impact is a powerful force that will continue to reshape global trade. The 15% shift is a clear indicator that the world economy is undergoing a fundamental transformation. Stakeholders must remain vigilant, adaptable, and strategically positioned to thrive in this evolving environment, recognizing that economic security is increasingly intertwined with geopolitical stability.
Conclusion: Navigating the New Global Trade Paradigm
The anticipated 15% shift in global trade flows by 2026, largely attributable to the enduring and evolving US Sanctions Impact, marks a critical juncture in international commerce. This is not a fleeting trend but a profound reordering of economic relationships that will have lasting consequences for nations, industries, and individual enterprises. We have explored the intricate dynamics behind this projection, from the historical evolution of US sanctions and their current strategic application, to the specific sectors and regions poised for significant realignment, and the diverse strategic responses being formulated globally.
The drivers of this shift are multifaceted, encompassing geopolitical tensions, technological competition, and a renewed emphasis on national security and economic sovereignty. The methodologies employed to forecast this magnitude of change combine sophisticated econometric models with expert geopolitical analysis, providing a robust foundation for the 15% figure. This comprehensive approach underscores that the impact extends far beyond simple trade rerouting; it involves fundamental changes in investment patterns, technological development, and financial architecture.
Key sectors such as high-tech manufacturing, energy, and financial services will undoubtedly experience the most direct and intense pressures, forcing rapid adaptation and innovation. Geographically, East Asia and Europe stand out as regions where the balancing act between traditional alliances and economic pragmatism will be most pronounced, leading to significant intra-regional consolidation and diversification away from traditional dependencies. Meanwhile, emerging economies in Latin America and Africa may find new opportunities as global supply chains and investment seek alternative pathways.
The strategic responses observed, from governmental efforts to bolster supply chain resilience and develop alternative payment systems, to corporate strategies emphasizing geographic diversification and robust compliance, highlight a global commitment to mitigating risks and seizing new opportunities. These actions collectively contribute to a future global trade paradigm that is likely to be more regionalized, potentially more resilient to single-point failures, but also more complex and potentially less integrated in certain aspects.
For businesses, the imperative is clear: proactive risk assessment, agile supply chain management, and a deep understanding of geopolitical currents are no longer optional but essential for survival and growth. For policymakers, the challenge lies in fostering an environment that balances national interests with the benefits of international cooperation, while navigating the delicate line between economic statecraft and the potential for global fragmentation.
As we move towards 2026 and beyond, the 15% shift will serve as a powerful reminder of how deeply intertwined politics and economics remain. The world is not simply adapting to sanctions; it is evolving to create a new normal where economic security is a paramount concern for all actors on the global stage. Those who can anticipate, understand, and strategically respond to the profound US Sanctions Impact will be best positioned to thrive in this emerging global trade landscape.
The discussions and analysis presented herein aim to equip readers with the knowledge necessary to navigate these turbulent yet transformative times. The future of global trade is being written now, and understanding the role of US sanctions in this narrative is more critical than ever.