U.S. Inflation Rate Holds Steady at 3.2% in February 2026: Expert Analysis on Consumer Spending
The economic landscape of the United States continues to be a subject of intense scrutiny, with inflation figures often taking center stage. In a development that has garnered significant attention from economists, policymakers, and the general public alike, the U.S. inflation rate held steady at 3.2% in February 2026. This stability, following a period of fluctuating economic indicators, offers both relief and a renewed sense of caution regarding the nation’s financial health. Understanding the nuances of this figure requires a deep dive into the underlying factors, particularly consumer spending, and an expert analysis of what these trends might signify for the future.
For months, the Federal Reserve and other financial institutions have been carefully monitoring inflation, aiming to guide the economy towards a sustainable growth path without triggering excessive price increases. The consistent 3.2% figure for February 2026 suggests that some of the monetary policy interventions and market adjustments may be yielding their intended effects, at least in terms of stabilizing the headline inflation number. However, as always, the devil is in the details, and a closer examination reveals a complex interplay of forces shaping the current economic environment. This article will provide a comprehensive overview of the current US inflation 2026 data, explore the role of consumer spending, and offer expert insights into what lies ahead.
Understanding the 3.2% US Inflation Rate in February 2026
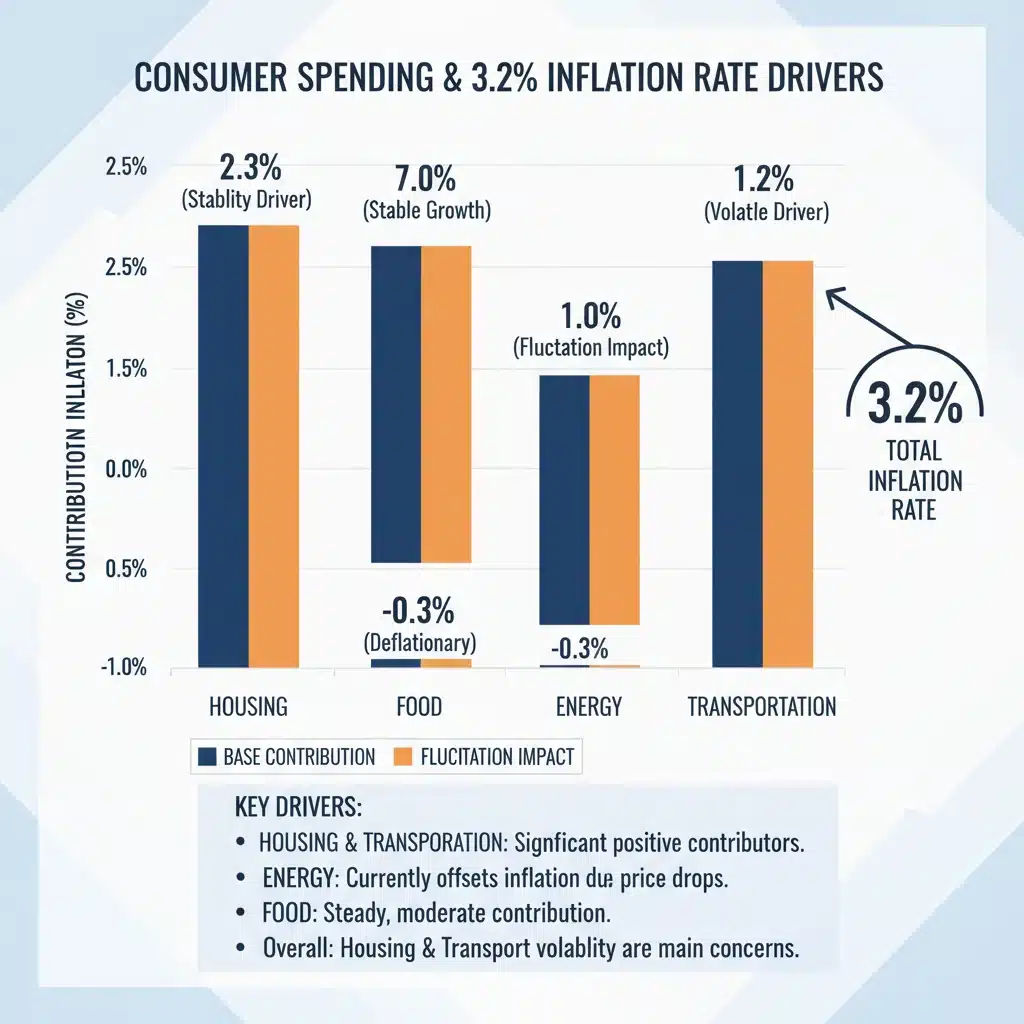
The headline US inflation 2026 rate, as measured by the Consumer Price Index (CPI), remaining at 3.2% in February 2026, is a key indicator that merits thorough examination. This figure represents the year-over-year increase in the average price of a basket of consumer goods and services. While 3.2% is still above the Federal Reserve’s long-term target of 2%, its stability is a notable change from the higher, more volatile rates observed in previous years. This consistency suggests that the rapid acceleration of prices seen during the post-pandemic recovery might be moderating, or at least entering a more predictable phase.
Several components contribute to the overall inflation rate, and a closer look at these individual categories can provide a more granular understanding. For February 2026, core inflation, which excludes volatile food and energy prices, also showed signs of stability, albeit at a slightly different level. This distinction is crucial because core inflation is often considered a better gauge of underlying inflationary pressures and long-term trends, as it filters out short-term shocks from commodity markets.
Factors influencing the stable 3.2% US inflation 2026 rate include a combination of supply-side improvements and demand-side adjustments. On the supply side, global supply chains, which were severely disrupted during the pandemic, have largely normalized. This has eased pressure on manufacturing and transportation costs, preventing further price hikes for many goods. Additionally, advancements in technology and automation continue to enhance productivity, potentially offsetting some labor cost increases.
On the demand side, while consumer spending remains robust, there are indications that its growth might be moderating from its peak. Interest rate hikes implemented by the Federal Reserve over the preceding years have made borrowing more expensive, which can cool down demand for big-ticket items like homes and cars. This deliberate tightening of monetary policy is designed to bring inflation back towards the target, and the February 2026 figures suggest it’s having an impact without tipping the economy into a recession.
However, it’s important to acknowledge that certain sectors continue to experience elevated price pressures. Services, particularly housing and healthcare, have shown more persistent inflation compared to goods. The housing market, despite higher interest rates, still faces supply constraints in many areas, keeping rental and homeownership costs elevated. Similarly, healthcare costs, driven by factors such as labor shortages and pharmaceutical advancements, often demonstrate an upward trend regardless of broader economic conditions.
The implications of a steady 3.2% US inflation 2026 rate are multi-faceted. For consumers, it means that while prices are still rising, the rate of increase is not accelerating, offering a degree of predictability in household budgeting. For businesses, it provides a more stable environment for planning and investment, reducing some of the uncertainty associated with rapid cost fluctuations. For policymakers, it presents a delicate balancing act: maintaining this stability while continuing to work towards the 2% target without stifling economic growth.
Consumer Spending: The Engine of the Economy
Consumer spending is undeniably the largest component of the U.S. economy, accounting for approximately two-thirds of the Gross Domestic Product (GDP). Therefore, any analysis of the US inflation 2026 rate must place significant emphasis on understanding current consumer spending patterns. The stability of inflation at 3.2% in February 2026 is intricately linked to how Americans are choosing to spend, save, and invest their money.
Recent data indicates a nuanced picture of consumer behavior. While overall spending remains strong, supporting economic activity, there are shifts occurring beneath the surface. Discretionary spending, which includes non-essential goods and services like entertainment, travel, and dining out, has shown resilience. This suggests that consumers, despite inflationary pressures, are still confident enough in their financial situations to indulge in experiences and non-necessities. Wage growth, while not uniformly distributed, has provided some households with increased purchasing power, contributing to this sustained demand.
However, the impact of higher interest rates and persistent inflation on household budgets cannot be overlooked. Many consumers are reportedly drawing down savings accumulated during the pandemic or relying more on credit to maintain their spending levels. This trend, if sustained, could pose risks to future economic stability. Increased reliance on credit could lead to higher debt burdens, potentially dampening future spending as households prioritize debt repayment.
Furthermore, the composition of consumer spending is shifting. There’s a noticeable move from goods to services, a continuation of a trend that began post-pandemic. As people feel safer and more comfortable engaging in social activities, spending on travel, hospitality, and personal services has surged. This shift explains why inflation in the services sector has been more persistent than in goods, where supply chain improvements have had a greater impact.
The labor market plays a critical role in underpinning consumer spending. A strong job market, characterized by low unemployment rates and consistent wage growth, provides consumers with the income and confidence needed to spend. In February 2026, the U.S. labor market continued to show robustness, albeit with some signs of cooling. While job growth remains positive, the pace has moderated, and wage increases, while still present, are not accelerating at the rates seen previously. This moderation is a delicate balance: strong enough to support spending but not so strong as to fuel a wage-price spiral that could reignite inflation.
Household balance sheets also provide crucial insights. While some households have depleted their excess savings, others, particularly those in higher income brackets, still possess significant financial buffers. This disparity in financial health means that the impact of inflation and interest rates is not felt uniformly across all demographics, leading to varied spending responses. Understanding these heterogeneous responses is vital for a comprehensive analysis of consumer behavior and its influence on the overall US inflation 2026 outlook.
Expert Analysis and Future Economic Outlook
The stability of the US inflation 2026 rate at 3.2% in February has elicited a range of reactions and analyses from leading economists and financial institutions. Many view this as a positive sign that the economy is navigating a ‘soft landing,’ where inflation gradually returns to target without a significant recession. However, others caution that underlying pressures could still lead to renewed volatility.
One prominent school of thought suggests that the Federal Reserve’s aggressive monetary tightening cycle has largely achieved its goal of bringing inflation under control. According to this perspective, the steady 3.2% rate is evidence that demand is cooling sufficiently to align with supply, and that further significant rate hikes may not be necessary. Some experts even speculate about the timing of potential rate cuts, suggesting that if inflation continues to stabilize or trend downwards, the Fed might consider easing policy later in 2026 to prevent an economic slowdown.
Conversely, another group of analysts maintains a more cautious stance. They argue that while the headline number is stable, the stickiness of services inflation, particularly in housing and healthcare, remains a concern. These sectors are less responsive to interest rate changes and are influenced by structural factors that are harder to address with conventional monetary policy. Therefore, they contend that the Fed might need to keep interest rates higher for longer to ensure inflation is definitively brought down to the 2% target. They also point to the potential for external shocks, such as geopolitical events or unexpected commodity price spikes, which could easily disrupt the current stability.
The role of fiscal policy also comes into play. Government spending and taxation decisions can significantly influence aggregate demand and, consequently, inflation. Any substantial shifts in fiscal policy in 2026 could either complement or counteract the Federal Reserve’s efforts, adding another layer of complexity to the economic outlook.
Looking ahead, several key indicators will be closely watched. Future CPI reports, particularly core inflation figures, will be critical in determining the trajectory of prices. Labor market data, including job growth, unemployment rates, and wage growth, will provide insights into the health of consumer demand and potential wage-price pressures. Consumer confidence surveys will offer a gauge of household sentiment and their willingness to spend. Business investment figures will indicate the private sector’s confidence in future economic conditions.
Most experts agree that the path to a sustained 2% inflation rate will not be linear. There will likely be periods of minor fluctuation, and the Federal Reserve will need to remain agile in its policy responses. The current stability at 3.2% provides a window of opportunity for careful assessment and strategic planning. The challenge for policymakers will be to fine-tune monetary policy to achieve the dual mandate of price stability and maximum sustainable employment, without overshooting or undershooting their targets.
Impact on Different Sectors and Industries
The stable US inflation 2026 rate at 3.2% in February has varied impacts across different sectors and industries. Understanding these sector-specific effects is crucial for businesses, investors, and policymakers.
The retail sector, heavily reliant on consumer spending, is experiencing a mixed bag. While persistent demand for discretionary items is a positive, higher borrowing costs for businesses and potentially for consumers (if they finance purchases) could temper growth. Retailers are also navigating shifts in consumer preferences, with a continued move towards online shopping and value-oriented purchases. Those who can adapt to these changes and manage their inventory efficiently will be better positioned.
The housing market remains a focal point. Despite higher mortgage rates, demand has shown resilience in many regions due to ongoing supply shortages. The 3.2% inflation rate, while stable, still contributes to elevated construction costs for materials and labor. This means that while existing home prices might stabilize or even slightly decline in some areas, new home construction faces cost pressures that can keep prices high. Rental markets also continue to see upward pressure, contributing significantly to the overall inflation rate.
The manufacturing sector benefits from easing supply chain constraints and more predictable input costs compared to previous years. However, energy prices, while more stable than their peaks, remain a factor for energy-intensive industries. Export-oriented manufacturers might also be affected by the strength of the U.S. dollar, which can make American goods more expensive for international buyers.
The financial services industry is directly impacted by the Federal Reserve’s interest rate policies. Banks and lenders are operating in an environment of higher interest rates, which can boost net interest margins but also increase the risk of loan defaults if economic conditions worsen. Investment firms are closely watching inflation trends to advise clients on asset allocation strategies, with a focus on inflation-hedging assets.
The technology sector, particularly growth-oriented companies, can be sensitive to interest rate environments. Higher rates increase the cost of capital, potentially making it more expensive for tech companies to fund expansion and innovation. However, the underlying demand for digital services and products remains strong, providing a resilient foundation for many tech firms.
The healthcare sector continues to face unique inflationary pressures. Labor shortages, particularly for skilled medical professionals, drive up wage costs. The cost of medical supplies, pharmaceuticals, and advanced equipment also contributes to rising healthcare expenditures. These costs are often passed on to consumers through higher insurance premiums or out-of-pocket expenses, making healthcare a persistent driver of services inflation.
The energy sector, while showing more stability in February 2026, remains susceptible to geopolitical events and global supply-demand dynamics. Stable inflation provides some relief, but any unforeseen disruptions could quickly reignite price volatility, impacting transportation costs and household utility bills. Businesses that can invest in renewable energy sources or improve energy efficiency may gain a competitive advantage.
Overall, the stable 3.2% US inflation 2026 rate offers a more predictable operating environment than the volatile periods of the recent past. However, businesses must remain agile, adapting their strategies to sector-specific challenges and opportunities. Diversification, efficient cost management, and a keen understanding of consumer behavior will be key to thriving in this economic climate.
Monetary Policy and the Federal Reserve’s Role
The Federal Reserve’s role in managing the US inflation 2026 rate cannot be overstated. Its primary tools—the federal funds rate, quantitative easing/tightening, and forward guidance—are meticulously employed to achieve its dual mandate of maximum employment and price stability. The steady 3.2% inflation rate in February 2026 is a direct reflection of the cumulative effects of the Fed’s monetary policy decisions over the past few years.
Following a period of aggressive interest rate hikes aimed at taming runaway inflation, the Fed has entered a more data-dependent phase. The decision to hold rates steady or make further adjustments is now heavily influenced by incoming economic data, including inflation reports, labor market statistics, and consumer sentiment. The February 2026 inflation data, showing stability, provides the Fed with some breathing room, allowing it to assess the impact of its previous actions more thoroughly.
The Fed’s communication, or ‘forward guidance,’ is also a powerful tool. By signaling its intentions regarding future interest rate paths, the Fed can influence market expectations and, consequently, long-term interest rates, borrowing costs, and investment decisions. In the current environment, the Fed is likely emphasizing a cautious and patient approach, reiterating its commitment to bringing inflation down to 2% while avoiding an unnecessary economic contraction.
One of the key debates within the Fed and among economists is the concept of the ‘neutral’ interest rate – the theoretical rate at which monetary policy is neither expansionary nor contractionary. Estimating this rate is challenging, but understanding it is crucial for determining whether current interest rates are restrictive enough to cool inflation without overly dampening economic activity. The stable 3.2% US inflation 2026 figure could suggest that policy is currently restrictive enough, or at least approaching that level.
The Fed also monitors various measures of inflation expectations. If consumers and businesses expect inflation to remain high, it can become a self-fulfilling prophecy, as workers demand higher wages and businesses raise prices. The stability in the current inflation rate helps to anchor these expectations, preventing a spiral of increasing prices and wages. This anchoring of inflation expectations is a critical success factor for monetary policy.
Looking ahead, the Federal Reserve faces a delicate balancing act. On one hand, persistent inflation, particularly in services, might necessitate maintaining a restrictive stance for longer than initially anticipated. On the other hand, overtightening could risk pushing the economy into a recession, leading to job losses and reduced consumer spending. The Fed’s decisions in the coming months will be pivotal in shaping the economic trajectory for the remainder of 2026 and beyond.
Market participants will be scrutinizing every statement from Fed officials, looking for clues about the future direction of monetary policy. The consensus view among many analysts is that the Fed will likely remain data-dependent, prioritizing inflation control while also being mindful of broader economic stability. The 3.2% US inflation 2026 rate for February offers a temporary reprieve, but the journey back to the 2% target is still ongoing, requiring continued vigilance and strategic adjustments.
Conclusion: Navigating the Economic Path Ahead
The U.S. inflation rate holding steady at 3.2% in February 2026 marks a significant moment in the nation’s ongoing economic narrative. It represents a period of relative stability after years of unprecedented volatility, offering a glimmer of hope that the economy is indeed on a path towards normalization. This stability is largely attributable to a combination of improving supply chains, moderating demand influenced by monetary policy, and resilient, albeit shifting, consumer spending patterns.
However, this stability should not be confused with a complete victory over inflation. The 3.2% rate is still above the Federal Reserve’s target, and underlying inflationary pressures, particularly in the services sector, persist. This means that while the immediate crisis of rapidly accelerating prices may have subsided, the journey to sustained price stability is far from over. The Federal Reserve will continue to play a crucial role, carefully calibrating its monetary policy to avoid both runaway inflation and an economic downturn.
Consumer spending, as the bedrock of the U.S. economy, will remain a critical variable. Its continued resilience, even with shifts towards services and a reliance on accumulated savings or credit, underscores the underlying strength of the American consumer. Yet, the long-term sustainability of these spending habits will depend on factors like wage growth, employment levels, and the overall health of household balance sheets.
For businesses, the current environment demands adaptability and strategic foresight. Understanding sector-specific impacts, managing costs effectively, and responding to evolving consumer preferences will be paramount. Investors, too, must remain vigilant, adjusting portfolios to account for ongoing inflationary pressures and potential shifts in monetary policy.
The February 2026 US inflation 2026 report serves as a crucial data point, painting a picture of an economy in transition. It suggests that the efforts to cool inflation are bearing fruit, but also highlights the complexity of achieving a perfect economic equilibrium. The path ahead will require continued vigilance from policymakers, prudent decision-making from businesses, and informed financial planning from consumers. While the stability at 3.2% is a welcome development, the focus must now shift to ensuring that this stability translates into sustainable, long-term economic prosperity for all.
The next few months will be critical in determining whether this steady inflation rate is a temporary plateau or a precursor to a sustained decline towards the Fed’s 2% target. All eyes will remain on forthcoming economic data, as the nation navigates this complex and ever-evolving economic landscape.