Social Security COLA 2026: 3.5% Increase for Beneficiaries
Social Security COLA 2026 Announced: A 3.5% Increase for Beneficiaries
The Social Security Administration (SSA) has recently announced a significant development for millions of Americans: a projected Social Security COLA 2026 (Cost-of-Living Adjustment) of 3.5%. This eagerly anticipated increase is set to impact the monthly benefits of retirees, disabled individuals, and other beneficiaries, offering a crucial boost in the face of ongoing economic fluctuations. Understanding the intricacies of this adjustment is vital for current and future beneficiaries alike, as it directly influences financial stability and planning.
For many, Social Security represents a primary, if not sole, source of income. Therefore, any adjustment, particularly an increase, holds immense importance. The 3.5% projection for the Social Security COLA 2026 reflects an ongoing effort to ensure that benefits keep pace with inflation, thereby preserving the purchasing power of beneficiaries. This article will delve into the details of this announcement, explore the mechanisms behind COLA calculations, discuss its potential impact, and provide insights into how beneficiaries can best prepare for these changes.
The concept of COLA was introduced to protect Social Security benefits from the erosive effects of inflation. Without these annual adjustments, the fixed income of beneficiaries would steadily lose value over time, making it increasingly difficult to cover essential living expenses. The Social Security COLA 2026 is a testament to this commitment, aiming to provide a necessary buffer against rising costs. Let’s unpack what this 3.5% increase truly signifies for the financial landscape of American seniors and individuals with disabilities.
Understanding the Social Security COLA: How It’s Calculated
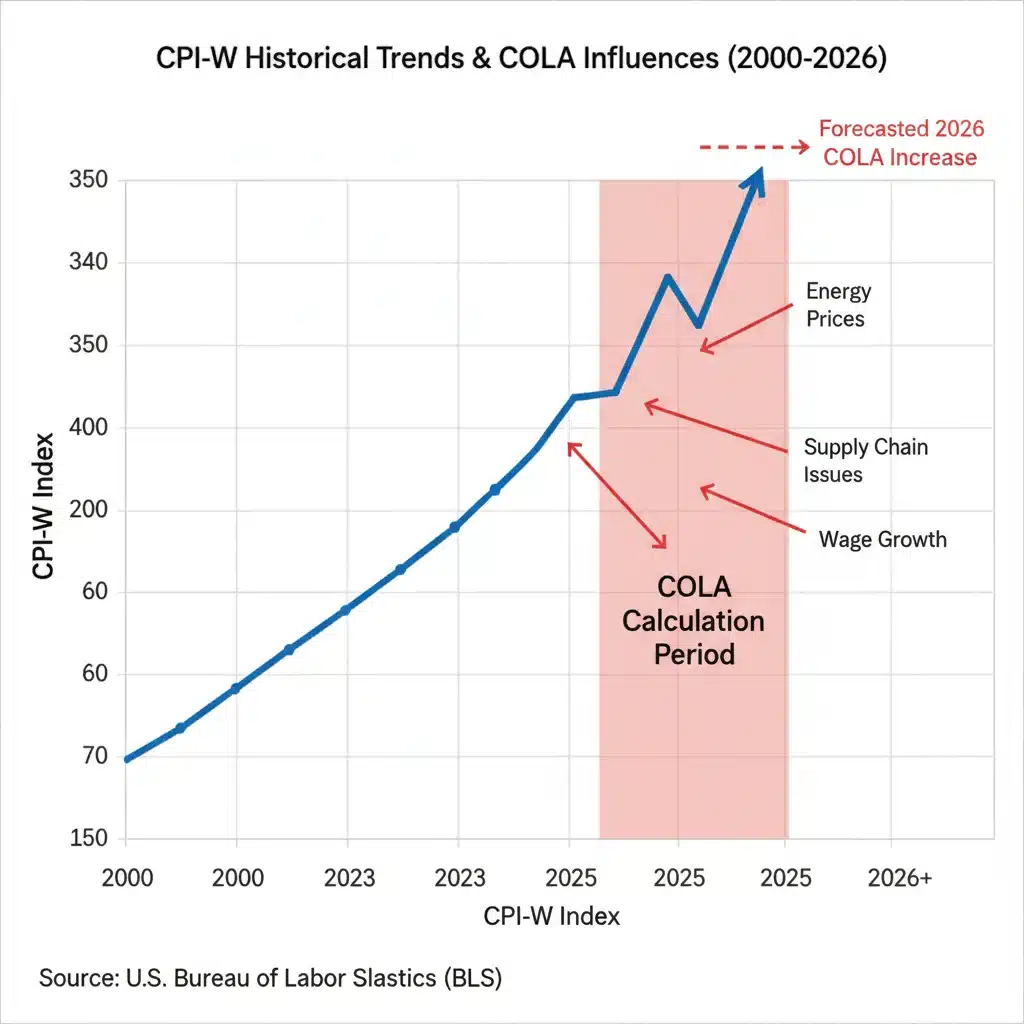
To fully grasp the significance of the Social Security COLA 2026, it’s essential to understand how these adjustments are determined. The annual COLA is calculated based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). This index measures the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services, including food, housing, apparel, transportation, medical care, recreation, and education.
Specifically, the COLA is determined by comparing the average CPI-W for the third quarter of the current year (July, August, and September) with the average CPI-W for the third quarter of the last year in which a COLA was effective. If there is an increase, the percentage difference, rounded to the nearest tenth of a percent, becomes the COLA for the following year. If there is no increase, or if the CPI-W decreases, there is no COLA for that year.
The 3.5% projection for the Social Security COLA 2026 is derived from current economic forecasts and inflationary trends observed in the CPI-W. It reflects the ongoing pressures of inflation that have been a significant concern for households across the nation. While not finalized until later in the year (typically October), these projections provide beneficiaries with an early indication of what to expect, allowing them to begin adjusting their financial plans accordingly. It’s crucial to note that while the CPI-W is used for COLA, it doesn’t perfectly mirror the spending patterns of all Social Security beneficiaries, particularly seniors who often have higher healthcare costs.
The history of COLA adjustments shows a dynamic response to economic conditions. In some years, beneficiaries have seen substantial increases, while in others, the adjustments have been minimal or even non-existent. The projected 3.5% increase for the Social Security COLA 2026 suggests a continued period of notable inflation, necessitating a robust adjustment to protect beneficiaries’ purchasing power.
The Impact of the 3.5% Social Security COLA 2026 on Beneficiaries
A 3.5% increase in Social Security benefits can have a tangible impact on the daily lives of millions. For an average beneficiary, this translates to a noticeable boost in monthly income, which can help offset rising costs for essentials such as groceries, utilities, and healthcare. Let’s consider a few scenarios to illustrate the potential effects of the Social Security COLA 2026.
For instance, if an individual currently receives $1,700 per month in Social Security benefits, a 3.5% increase would add approximately $59.50 to their monthly payment, bringing their new total to $1,759.50. While this might seem modest to some, for those living on a fixed income, every dollar makes a difference. Over the course of a year, this equates to an additional $714, which can be invaluable for covering unexpected expenses, medical co-pays, or simply providing a bit more breathing room in a tight budget.
However, it’s important to consider that a COLA increase can also have secondary effects. For some beneficiaries, a higher income might push them into a different tax bracket, potentially leading to a larger portion of their Social Security benefits being subject to federal income tax. The thresholds for taxing Social Security benefits are not adjusted for inflation, meaning that a COLA increase can inadvertently lead to more benefits being taxed. This is a critical factor for beneficiaries to consider when evaluating the net impact of the Social Security COLA 2026.
Furthermore, the increase could affect eligibility for certain income-tested programs, such as Medicaid or Supplemental Security Income (SSI). While SSI has its own COLA, the increase in regular Social Security benefits could push some individuals over the income limits for other assistance programs, requiring careful financial planning and review of eligibility criteria.
The Social Security COLA 2026 also plays a role in the broader economy. When beneficiaries have more disposable income, it can stimulate local economies as they spend more on goods and services. This ripple effect can benefit small businesses and contribute to overall economic activity. Therefore, the COLA is not just a benefit adjustment; it’s an economic stabilizer.
Historical Context and Future Projections for COLA
To fully appreciate the Social Security COLA 2026, it’s beneficial to look at historical COLA adjustments. In recent years, we’ve seen a range of increases, reflecting varying economic conditions. For instance, the COLA for 2022 was a substantial 5.9%, followed by an even larger 8.7% for 2023, largely due to high inflation rates experienced during those periods. The 2024 COLA saw a more moderate 3.2% increase, and the 2025 projection is currently around 2.6%. The projected 3.5% for 2026 indicates a slight rebound in inflationary pressures compared to the 2025 forecast, but still lower than the peaks of 2022 and 2023.
These fluctuations underscore the dynamic nature of the economy and its direct influence on Social Security benefits. The Social Security COLA 2026 is a forward-looking measure, attempting to predict and compensate for future inflation, based on current data. This proactive approach is crucial for maintaining the financial well-being of beneficiaries.
Future projections for COLA are subject to change as economic data evolves. Factors such as global supply chain issues, energy prices, wage growth, and geopolitical events can all influence inflation and, consequently, the CPI-W. Therefore, while the 3.5% projection for the Social Security COLA 2026 provides a strong indication, beneficiaries should remain aware that the final figure could shift slightly based on the CPI-W data collected in the third quarter of 2025.
Long-term trends suggest that while inflation can be volatile year-to-year, it generally tends to rise over time. This makes the COLA mechanism a critical component of Social Security, ensuring its long-term viability and relevance as a safety net. Without it, the real value of benefits would diminish significantly over a beneficiary’s retirement years, leading to increased financial hardship.
Preparing for the Social Security COLA 2026: Tips for Beneficiaries
With the projected 3.5% Social Security COLA 2026 on the horizon, now is an excellent time for beneficiaries to review their financial plans and make necessary adjustments. Here are some practical tips:
- Review Your Budget: Re-evaluate your monthly budget to incorporate the increased income. Identify areas where the extra funds can be most effectively utilized, whether it’s for essential expenses, debt reduction, or discretionary spending.
- Understand Tax Implications: Consult with a tax professional to understand how the increased benefits might affect your federal income tax liability. As mentioned, higher income could lead to a larger portion of your Social Security benefits being taxed.
- Assess Impact on Other Benefits: If you receive other government assistance programs, check how the COLA increase might affect your eligibility or benefit amounts for those programs.
- Adjust Savings and Investments: Consider allocating any surplus funds from the COLA increase to savings or investments. Even small, consistent contributions can grow significantly over time.
- Monitor Healthcare Costs: While Social Security benefits increase, so do healthcare costs. Factor in potential increases in Medicare premiums (which are often deducted directly from Social Security benefits) and other medical expenses when planning your budget.
- Stay Informed: Keep an eye on official announcements from the Social Security Administration regarding the final COLA figure, typically released in October.
Proactive planning is key to maximizing the benefits of the Social Security COLA 2026. By understanding the potential impacts and making informed decisions, beneficiaries can ensure their financial well-being is maintained and even improved.
The Broader Economic Context and Social Security’s Future
The Social Security COLA 2026 doesn’t exist in a vacuum; it’s a reflection of the broader economic landscape. Inflationary pressures, while challenging, also indicate a dynamic economy with potential wage growth and consumer demand. However, persistent inflation can erode purchasing power, making COLA adjustments critically important.
Beyond the immediate impact of the 3.5% increase, discussions about the long-term solvency of Social Security continue. While COLA helps beneficiaries cope with rising costs, it also adds to the program’s expenditures. Debates often revolve around potential reforms, such as adjusting the full retirement age, modifying the COLA calculation method, or increasing the Social Security tax cap. These discussions are complex and involve balancing the needs of current beneficiaries with the sustainability of the program for future generations.
The Social Security COLA 2026 highlights the ongoing need for a robust and adaptable Social Security system. As demographics shift and economic conditions evolve, continuous evaluation and thoughtful policy adjustments will be essential to ensure that Social Security remains a cornerstone of financial security for millions of Americans. Beneficiaries and taxpayers alike have a vested interest in these discussions, as the future of Social Security impacts everyone.
Understanding the interplay between inflation, the CPI-W, and COLA adjustments empowers individuals to engage more effectively in these broader conversations and advocate for policies that support their financial well-being. The 3.5% increase for the Social Security COLA 2026 is not just a number; it’s a vital component of a larger system designed to provide security and stability.
Frequently Asked Questions About Social Security COLA 2026
When will the 3.5% Social Security COLA 2026 be finalized?
The official announcement for the Social Security COLA 2026 is typically made in October of the preceding year (i.e., October 2025). The 3.5% is a projection based on current economic data, but the final figure will depend on the CPI-W data for July, August, and September 2025.
Will the COLA increase affect my Medicare premiums?
Yes, Medicare Part B premiums are often deducted directly from Social Security benefits. While the COLA increases your gross benefit, the new Part B premium for 2026 (usually announced in the fall of 2025) will also be deducted. For some beneficiaries, the increase in Medicare premiums can offset a portion of their COLA increase, though a ‘hold harmless’ provision generally prevents Part B premiums from reducing a beneficiary’s net Social Security payment below the previous year’s level if they are subject to premium increases.
How does the Social Security COLA 2026 compare to previous years?
The projected 3.5% Social Security COLA 2026 is lower than the significant increases seen in 2022 (5.9%) and 2023 (8.7%), which were driven by exceptionally high inflation. It is slightly higher than the 3.2% COLA for 2024 and the current projection for 2025 (around 2.6%), indicating a moderate but sustained inflationary environment.
Are all Social Security benefits adjusted by COLA?
Yes, COLA applies to all Social Security benefits, including those for retirees, survivors, and individuals with disabilities. Supplemental Security Income (SSI) benefits also receive a COLA, which is usually the same percentage as the Social Security COLA.
What should I do if I have questions about my specific benefits?
For personalized information regarding your Social Security benefits, including the impact of the Social Security COLA 2026 on your specific situation, it is best to contact the Social Security Administration directly through their official website (SSA.gov), by phone, or by visiting a local office. You can also create a ‘my Social Security’ account online to view your benefits statement and other important information.
Conclusion: Navigating the Social Security COLA 2026
The projected 3.5% Social Security COLA 2026 is a vital adjustment designed to help millions of beneficiaries maintain their purchasing power in an evolving economic landscape. This increase, while not as dramatic as some recent years, still represents a significant boost for those relying on Social Security for their financial stability.
Understanding how COLA is calculated, its potential impact on personal finances and other benefits, and how to proactively plan for these changes is crucial. By staying informed and taking strategic steps, beneficiaries can effectively navigate the implications of the Social Security COLA 2026 and ensure their financial well-being is protected. As the official announcement draws closer, continued vigilance and informed decision-making will empower beneficiaries to make the most of this important adjustment.
The Social Security system, with its built-in COLA mechanism, remains a cornerstone of financial security for American families. The Social Security COLA 2026 is another chapter in its ongoing mission to provide a safety net, adapting to the economic realities faced by those it serves.