Navigating Student Loan Repayment in 2026: Public vs. Private Benefits
The landscape of higher education finance is constantly evolving, and for millions of Americans, student loans remain a significant financial burden. As we look ahead to 2026, understanding the nuances of student loan repayment 2026, particularly the distinctions between public and private options, is more crucial than ever. This comprehensive guide will delve into the projected benefits, challenges, and strategic considerations for borrowers facing their repayment journeys in the coming year. Whether you’re a recent graduate or a seasoned borrower, deciphering the complexities of these financial instruments is key to securing your financial future.
The choices made today regarding your student loan repayment strategy can have long-lasting implications. Public and private loans, while both serving the purpose of funding education, operate under vastly different frameworks. These differences extend to interest rates, repayment plans, borrower protections, and potential for forgiveness. In 2026, we anticipate continued adjustments and potential new legislative actions that could further shape these options. Therefore, staying informed about the most current policies and programs is paramount. This article aims to equip you with the knowledge needed to make the most informed decisions about your student loan repayment in 2026.
We will explore the specific characteristics of federal student loans, including their various income-driven repayment (IDR) plans, forbearance, deferment options, and the often-sought-after forgiveness programs. Concurrently, we will examine private student loans, highlighting their typically less flexible terms, reliance on credit scores, and the limited avenues for relief. By the end of this discussion, you will have a clearer understanding of which type of loan offers what, and how to leverage these insights to optimize your student loan repayment 2026 plan.
Understanding Federal Student Loan Repayment in 2026
Federal student loans, issued by the U.S. Department of Education, are generally considered the more borrower-friendly option due to their robust set of protections and flexible repayment plans. As we move into 2026, many of these benefits are expected to remain, with potential enhancements or modifications. Key features that define federal loan repayment include:
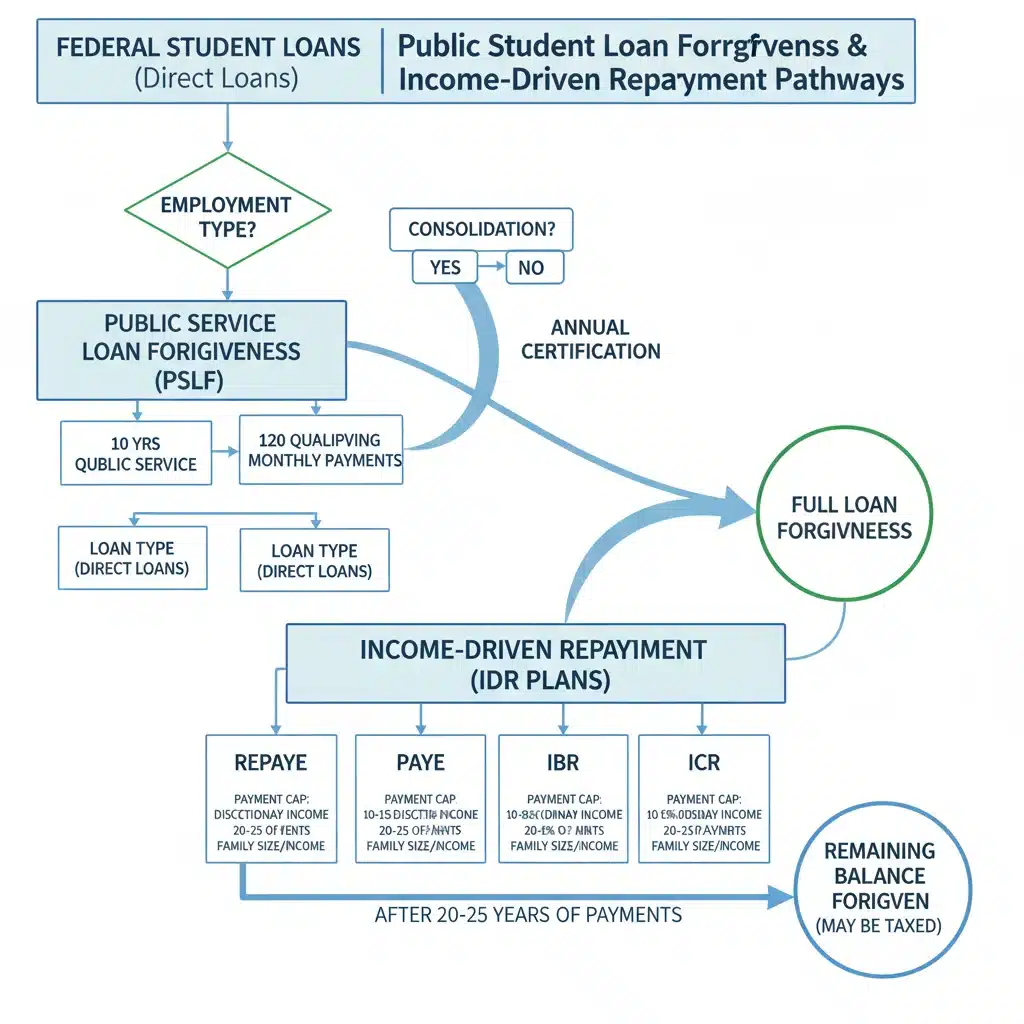
- Income-Driven Repayment (IDR) Plans: These plans adjust your monthly payment based on your income and family size, making repayment more manageable during periods of lower earnings. Common IDR plans include PAYE, REPAYE (which is being replaced by SAVE in some capacities, potentially fully by 2026), IBR, and ICR. The SAVE Plan, in particular, is designed to significantly lower monthly payments for many borrowers, and its full implementation and impact by 2026 will be a critical factor for many. It’s crucial to understand how these plans calculate discretionary income and what percentage of that income is applied to your payments. For example, under the SAVE plan, the percentage of discretionary income used to calculate payments for undergraduate loans is being reduced from 10% to 5%, which could lead to substantial savings for many borrowers.
- Loan Forgiveness Programs: Federal loans offer several pathways to forgiveness, including Public Service Loan Forgiveness (PSLF) for those working in qualifying public service jobs, and forgiveness after 20 or 25 years of payments on an IDR plan. The eligibility requirements for these programs can be stringent, but for those who qualify, they offer a powerful incentive and a path to debt-free living. Understanding the specific criteria, such as the type of employer, full-time employment status, and the number of qualifying payments, is essential for borrowers pursuing these options.
- Deferment and Forbearance: These options allow borrowers to temporarily pause or reduce their payments under specific circumstances, such as unemployment, economic hardship, or military service. While interest may accrue during these periods, they provide a vital safety net for borrowers experiencing financial difficulties. It’s important to differentiate between deferment, where interest may or may not accrue depending on the loan type, and forbearance, where interest almost always accrues.
- Fixed Interest Rates: Federal student loans typically come with fixed interest rates, meaning your rate won’t change over the life of the loan. This provides predictability and stability in your monthly payments, which is a significant advantage over variable-rate private loans.
- Loan Consolidation: Borrowers can consolidate multiple federal loans into a single Direct Consolidation Loan, which can simplify repayment and potentially open doors to additional repayment plans or forgiveness options. However, consolidation can sometimes extend the repayment period and may cause you to lose certain borrower benefits associated with the original loans, so careful consideration is advised.
The federal government continuously reviews and updates its student loan policies. Borrowers should remain vigilant for any new legislation or program changes that could impact their student loan repayment 2026 strategies. Official sources like the Department of Education website are the best places to find the most up-to-date information.
Navigating Private Student Loan Repayment in 2026
Private student loans are offered by banks, credit unions, and other financial institutions. Unlike federal loans, they are not backed by the government and therefore come with different terms and fewer borrower protections. In 2026, the landscape for private student loan repayment is expected to largely mirror current trends, with a strong emphasis on creditworthiness and market-driven interest rates.
Key Characteristics of Private Student Loans:
- Credit-Based Eligibility: Private loans are typically credit-based, meaning approval and interest rates depend heavily on the borrower’s (and often a co-signer’s) credit score and financial history. This can be a barrier for students with limited credit history or lower scores.
- Variable and Fixed Interest Rates: While some private lenders offer fixed rates, many also offer variable rates, which can fluctuate with market conditions. A variable rate might start lower but can increase over time, making monthly payments unpredictable and potentially more expensive.
- Limited Repayment Flexibility: Private lenders generally offer fewer options for repayment flexibility compared to federal loans. Income-driven repayment plans are rare, and deferment or forbearance options are often less generous and depend entirely on the lender’s discretion.
- No Federal Forgiveness Programs: Private student loans are not eligible for federal loan forgiveness programs like PSLF or IDR forgiveness. This is a critical distinction for borrowers considering career paths in public service or those anticipating long-term financial hardship.
- Refinancing Opportunities: One significant aspect of private loans (and a strategy for federal loans as well, though with trade-offs) is refinancing. In 2026, competitive rates from private lenders could make refinancing an attractive option for borrowers with good credit seeking to lower their interest rate or consolidate multiple loans into a single payment. However, refinancing federal loans into private loans means forfeiting all federal protections.
For those with private student loans, proactive management is key. This includes regularly checking interest rates, exploring refinancing options if your credit score has improved, and maintaining open communication with your lender if you anticipate repayment difficulties. Understanding the terms of your specific loan agreement is paramount, as there is far less standardization across private lenders compared to federal programs when it comes to student loan repayment 2026.
Comparing Benefits: Public vs. Private Student Loan Repayment Assistance Programs in 2026
The fundamental difference between public (federal) and private student loans lies in their core purpose and the entity backing them. Federal loans are designed with a social mission, aiming to make higher education accessible and manageable for a wide range of students, irrespective of their credit history, and offering extensive safety nets. Private loans, on the other hand, are commercial products offered by financial institutions with a profit motive, and thus their terms are primarily dictated by market forces and borrower creditworthiness.
Flexibility and Borrower Protections:
Federal loans unequivocally offer superior flexibility and borrower protections. The array of income-driven repayment plans ensures that payments remain affordable, even if a borrower’s income fluctuates. The ability to pause payments through deferment or forbearance, with specific conditions, provides a crucial safety net during unforeseen financial hardships. Furthermore, the existence of federal loan forgiveness programs, such as Public Service Loan Forgiveness (PSLF) or forgiveness after a specified period on an IDR plan, offers a tangible pathway to debt relief for many. These protections are a cornerstone of federal student loan repayment 2026 strategies.
Private loans, in contrast, offer minimal flexibility. Repayment terms are generally fixed, and while some lenders might offer temporary hardship programs, they are not guaranteed and are often less generous than federal options. There are no inherent loan forgiveness programs for private loans, making the path to debt relief solely dependent on full repayment or successful refinancing.
Interest Rates and Loan Costs:
Federal student loans typically offer fixed interest rates that are often lower than those found on private loans, especially for borrowers with less-than-perfect credit. The rates are set by Congress and are usually tied to economic indicators, but they remain constant once the loan is disbursed. This predictability is a significant advantage for budgeting and long-term financial planning.
Private loan interest rates can vary widely. While borrowers with excellent credit might secure very competitive fixed or variable rates, those with average or poor credit will often face much higher rates. The risk associated with variable rates, which can increase over time, adds another layer of uncertainty to private loan repayment. In 2026, market interest rate fluctuations could significantly impact the cost of variable-rate private loans.
Impact of Legislative Changes:
Federal student loan programs are subject to legislative changes, which can introduce new benefits or modify existing ones. For instance, the ongoing implementation and refinement of the SAVE Plan represent a significant shift in federal loan repayment. Borrowers need to stay informed about potential new laws or administrative actions that could affect their federal loans in 2026. These changes can offer new opportunities for relief or require adjustments to repayment strategies.
Private loans are less directly affected by federal legislative changes, though broader economic policies (like changes in the federal funds rate) can influence their interest rates and the overall lending environment. The terms of private loans are primarily governed by the contract between the borrower and the lender, making them less susceptible to government-mandated adjustments to repayment plans or forgiveness options.
Strategic Considerations for Student Loan Repayment in 2026
Given the distinct characteristics of public and private loans, a strategic approach to student loan repayment 2026 is essential. Your strategy should be tailored to your specific financial situation, career goals, and the types of loans you hold.
For Federal Loan Borrowers:
- Understand the SAVE Plan and Other IDR Options: If you have federal loans, thoroughly research the SAVE Plan and determine if it offers the lowest monthly payment and the most favorable terms for your situation. Compare it with other IDR plans like PAYE, IBR, and ICR, as one might be more advantageous depending on your income and loan balance.
- Explore Forgiveness Programs: If you work in public service, diligently track your qualifying payments for PSLF. For others, understand the timeline and requirements for forgiveness under IDR plans. Ensure you are enrolled in a qualifying IDR plan and make consistent, on-time payments.
- Consolidate Strategically: Consider federal loan consolidation if it simplifies your payments or makes you eligible for certain IDR plans or forgiveness programs. Be aware of the implications, such as potentially resetting your payment count for forgiveness.
- Utilize Deferment/Forbearance Wisely: Use these options only when absolutely necessary, as interest may accrue, increasing your total debt. Always explore IDR plans first, as they can offer $0 payments without the interest capitalization that often accompanies forbearance.
For Private Loan Borrowers:
- Monitor Interest Rates and Refinance Opportunities: Regularly check current interest rates from various private lenders. If your credit score has improved or market rates have dropped, refinancing could significantly reduce your interest payments or shorten your repayment term.
- Consider Co-signer Release: If you have a co-signer, many lenders offer a co-signer release option after a certain number of on-time payments. Pursuing this can relieve your co-signer of their obligation.
- Communicate with Your Lender: If you anticipate financial difficulty, contact your private lender immediately. While their options are limited, they might offer temporary payment adjustments or short-term forbearance.
- Prioritize High-Interest Loans: If you have multiple private loans, consider focusing extra payments on the loan with the highest interest rate to save money over the long term (the ‘debt avalanche’ method).
For Borrowers with Both Federal and Private Loans:
Many individuals hold both federal and private student loans. In such cases, a hybrid strategy is often the most effective. Generally, it’s advisable to prioritize managing your federal loans under the most beneficial IDR or forgiveness plan, while simultaneously addressing private loans with a focus on minimizing interest and exploring refinancing.
Do not refinance federal loans into private loans without fully understanding the loss of federal protections. While a lower interest rate might seem appealing, the flexibility and safety nets of federal loans are invaluable, especially in uncertain economic times. The decision to refinance federal loans should be carefully weighed against the potential loss of IDR plans, forgiveness options, and deferment/forbearance benefits.
Anticipated Changes and Future Outlook for 2026
The year 2026 is likely to see further developments in student loan policy. While predicting exact legislative outcomes is challenging, several areas warrant attention:
- Full Implementation of the SAVE Plan: The SAVE Plan is still in its early stages of implementation, with some provisions slated for full rollout in July 2024. By 2026, its full impact on borrower payments and forgiveness timelines will be clearer, and it may become the dominant IDR plan.
- Potential for New Legislation: The political climate surrounding student debt could lead to new legislative proposals. These might include further reforms to forgiveness programs, adjustments to interest rates, or new forms of borrower relief. Staying informed about these discussions is crucial.
- Economic Factors: Broader economic conditions, such as inflation rates, interest rate policies by the Federal Reserve, and employment levels, will influence both federal and private loan markets. These factors can affect the cost of borrowing, the attractiveness of refinancing, and the ability of borrowers to make payments.
- Technological Advancements: Digital tools and platforms for loan management are continually evolving. In 2026, we might see more sophisticated online portals, AI-driven advice, and streamlined application processes for various repayment programs.
Borrowers should make it a point to regularly check official government websites, reputable financial news sources, and their loan servicer’s communications for updates. Proactive engagement with your student loans, rather than passive acceptance, will be your greatest asset in navigating student loan repayment 2026.
Common Pitfalls to Avoid in Student Loan Repayment
While understanding the benefits is crucial, it’s equally important to be aware of common mistakes that can derail your repayment efforts:
- Ignoring Your Loans: Burying your head in the sand is perhaps the worst strategy. Unpaid loans can lead to default, severely damaging your credit score and resulting in wage garnishment, tax refund offset, and even loss of professional licenses.
- Not Knowing Your Loan Types: Mistaking a private loan for a federal one, or vice-versa, can lead to missed opportunities for assistance or unexpected financial burdens. Always know exactly what type of loans you have.
- Missing Payments: Even one missed payment can incur late fees and negatively impact your credit score. If you anticipate difficulty, proactively contact your servicer or lender to explore options.
- Refinancing Federal Loans Without Understanding Consequences: As mentioned, refinancing federal loans into private ones means losing valuable federal protections. This decision should only be made after careful consideration and if you are confident you will not need those federal benefits.
- Not Updating Contact Information: Ensure your loan servicer or lender always has your current contact details. Missing important communications can lead to missed deadlines for applications or critical updates on your loan status.
- Falling for Scams: Be wary of companies promising quick fixes or guaranteed loan forgiveness for a fee. Most federal loan programs can be accessed directly through your servicer or the Department of Education at no cost.
Actionable Steps for 2026 Student Loan Repayment
To prepare for and effectively manage your student loan repayment 2026, consider these actionable steps:
- Inventory Your Loans: Create a detailed list of all your student loans, noting whether they are federal or private, the interest rate, current balance, and servicer. For federal loans, visit studentaid.gov.
- Review Your Repayment Plan: For federal loans, log into your servicer’s portal and explore all available repayment plans, especially the SAVE Plan. Use the Loan Simulator tool on studentaid.gov to compare options.
- Assess Your Financial Situation: Create a realistic budget. Understand your income, expenses, and how much you can comfortably allocate to loan payments.
- Consider Refinancing for Private Loans: If you have private loans and a strong credit score, research refinancing options to potentially lower your interest rate or monthly payment.
- Build an Emergency Fund: Having a financial cushion can prevent you from needing to use deferment or forbearance, which can lead to increased interest.
- Stay Informed: Regularly check official sources for updates on student loan policies and programs. Subscribe to newsletters from your servicer and the Department of Education.
- Seek Professional Advice: If your situation is complex, consider consulting with a non-profit credit counselor or a financial advisor specializing in student loans.
Conclusion: Empowering Your 2026 Student Loan Journey
The journey of student loan repayment 2026, while potentially daunting, is manageable with the right knowledge and strategy. The critical distinction between public and private student loans and their respective benefits is the cornerstone of effective debt management. Federal loans offer a safety net of flexible repayment plans and forgiveness programs, designed to support borrowers through various life stages and career paths. Private loans, while lacking these extensive protections, can offer competitive rates for creditworthy borrowers and opportunities for refinancing.
As we approach 2026, the landscape will continue to evolve. New policies, economic shifts, and personal circumstances will all play a role in shaping your repayment experience. By proactively understanding your loan types, exploring all available options, and staying informed about legislative changes, you empower yourself to make the best financial decisions. Remember, your goal is not just to repay your loans, but to do so in a way that aligns with your broader financial goals and ensures a stable future. Take the time to evaluate, plan, and adjust your strategy as needed, and you will successfully navigate the complexities of student loan repayment in 2026 and beyond.