The Rise of Digital Currencies: How 3 Global Trends Will Shape U.S. Economic Stability by 2026
The financial landscape is undergoing a profound transformation, driven by the relentless innovation in digital currencies. From the speculative highs of cryptocurrencies like Bitcoin and Ethereum to the measured march towards Central Bank Digital Currencies (CBDCs), the global economy is bracing for a new era. The United States, as a pivotal player in the world financial system, faces a critical juncture. The decisions made and trends embraced (or resisted) in the coming years will significantly dictate U.S. economic stability by 2026. This article delves into the intricate relationship between the rise of digital currencies and the future of the American economy, focusing on three overarching global trends that will profoundly influence this trajectory. Understanding the digital currency impact is no longer an academic exercise; it’s an imperative for policymakers, businesses, and individuals alike.
The concept of money itself is evolving. For centuries, physical cash and traditional bank transfers have been the bedrock of commerce. However, the digital age has introduced new paradigms, challenging established norms and offering both unprecedented opportunities and significant risks. The decentralized nature of many cryptocurrencies promises greater financial inclusion and censorship resistance, while government-backed CBDCs aim to modernize payment systems, enhance monetary policy effectiveness, and combat illicit finance. The confluence of these forces creates a dynamic and often unpredictable environment, making it crucial to analyze the specific trends that will define the next few years for U.S. economic stability.
By 2026, the global financial architecture will likely look very different from today. The pace of change is accelerating, fueled by technological advancements, geopolitical shifts, and evolving consumer preferences. The U.S. cannot afford to be a passive observer in this digital revolution. Its economic resilience, its role as a global financial leader, and the well-being of its citizens will depend on its ability to navigate this complex terrain. Let’s explore the key global trends that will shape the digital currency impact on U.S. economic stability.
Trend 1: The Global Race for Central Bank Digital Currencies (CBDCs) and Its Implications for the Dollar’s Hegemony
One of the most significant global trends influencing the digital currency impact on U.S. economic stability is the accelerating development and potential deployment of Central Bank Digital Currencies (CBDCs) by major economies worldwide. While the U.S. Federal Reserve has been cautiously exploring a potential digital dollar, other nations, most notably China with its digital yuan (e-CNY), are already advanced in their pilot programs or even in broader deployment. This global race has profound implications for the U.S. dollar’s long-standing status as the world’s primary reserve currency and its role in international trade.
The Digital Yuan’s Challenge to the Dollar
China’s rapid progress with the digital yuan is a case in point. The e-CNY is not a cryptocurrency in the traditional sense; it is a digital form of fiat currency issued and controlled by the People’s Bank of China. Its primary goals include modernizing China’s payment infrastructure, enhancing financial inclusion, and potentially circumventing U.S.-dominated international payment systems like SWIFT. While the digital yuan is currently focused on domestic use, its long-term potential for cross-border transactions could offer an alternative to the dollar for countries seeking to reduce their reliance on the U.S. financial system.
If more countries begin to settle international trade in digital yuan or other CBDCs, the demand for U.S. dollars could gradually diminish. This decline in demand would have several significant consequences for U.S. economic stability. Firstly, it could reduce the U.S. government’s ability to finance its debt at low interest rates, as foreign demand for U.S. Treasury bonds might wane. Secondly, it could weaken the dollar’s exchange rate, making imports more expensive and potentially fueling inflation. Thirdly, it could diminish the U.S.’s geopolitical leverage, as the ability to impose financial sanctions is largely tied to the dollar’s dominance.
U.S. Response and the Digital Dollar’s Potential
The U.S. response to this global trend is critical. A thoughtfully designed digital dollar could offer numerous benefits, including faster and cheaper domestic payments, enhanced financial inclusion for the unbanked, and potentially a more resilient payment system. However, concerns around privacy, cybersecurity, and the potential impact on commercial banks have led to a more cautious approach. The debate within the U.S. centers on whether a digital dollar is necessary to maintain the dollar’s global standing or if existing private sector innovations can adequately meet evolving payment needs.
By 2026, the landscape of global CBDCs will likely be much clearer. If the U.S. lags significantly in its CBDC development, it risks ceding ground in the digital financial sphere, potentially eroding the dollar’s hegemony and introducing new vulnerabilities to U.S. economic stability. The digital currency impact here is not just about technology; it’s about geopolitical power and monetary sovereignty.
Trend 2: The Maturation and Regulatory Scrutiny of Decentralized Finance (DeFi) and Cryptocurrencies
The second major global trend shaping the digital currency impact on U.S. economic stability is the ongoing maturation of decentralized finance (DeFi) and the broader cryptocurrency ecosystem, coupled with intensified global regulatory scrutiny. What began as a niche technological experiment has evolved into a multi-trillion-dollar industry, attracting significant institutional investment and mainstream attention. However, its rapid growth has also exposed vulnerabilities, leading to calls for comprehensive regulation.
DeFi’s Promise and Perils
DeFi applications, built on blockchain technology, aim to recreate traditional financial services (lending, borrowing, trading, insurance) without intermediaries like banks. Proponents argue that DeFi offers greater transparency, efficiency, and accessibility. Its global, 24/7 nature means that financial activity is no longer confined by national borders or traditional banking hours. This global reach means that financial innovations and crises in one part of the DeFi ecosystem can quickly propagate across the world, potentially impacting U.S. markets.
However, DeFi also presents significant risks. The lack of robust regulatory oversight has led to instances of fraud, market manipulation, and consumer losses. High volatility, technical vulnerabilities (e.g., smart contract bugs), and the potential for illicit finance (money laundering, terrorist financing) are major concerns for regulators globally. The collapse of major crypto entities and stablecoins in recent years has highlighted the interconnectedness of the crypto market and its potential to spill over into traditional finance, albeit on a limited scale so far.
Global Regulatory Convergence and Divergence
Governments and international bodies are grappling with how to regulate this nascent industry. There is a growing consensus that some form of regulation is necessary to protect investors, ensure market integrity, and mitigate systemic risks. However, the approach to regulation varies significantly across jurisdictions. Some countries have adopted a more permissive stance, aiming to foster innovation, while others have implemented strict bans or highly restrictive frameworks. This divergence creates regulatory arbitrage opportunities and challenges for global enforcement.
For the U.S., the challenge lies in developing a comprehensive and consistent regulatory framework that balances innovation with consumer protection and financial stability. The SEC, CFTC, Treasury, and other agencies are all involved, often with overlapping jurisdictions. Clarifying which digital assets are securities, commodities, or something else entirely is a critical step. Failure to establish clear rules could stifle innovation, drive crypto businesses offshore, or, conversely, allow unchecked risks to build up, potentially threatening U.S. economic stability.
By 2026, it is highly probable that a more defined global regulatory landscape for DeFi and cryptocurrencies will emerge. The extent to which this regulation is harmonized internationally and how effectively the U.S. integrates it will determine the industry’s trajectory and its ultimate digital currency impact on the traditional financial system. A well-regulated crypto market could unlock new capital formation and payment efficiencies, while a poorly regulated one could introduce systemic fragilities.
Trend 3: The Integration of Digital Currencies into Cross-Border Payments and Trade Finance
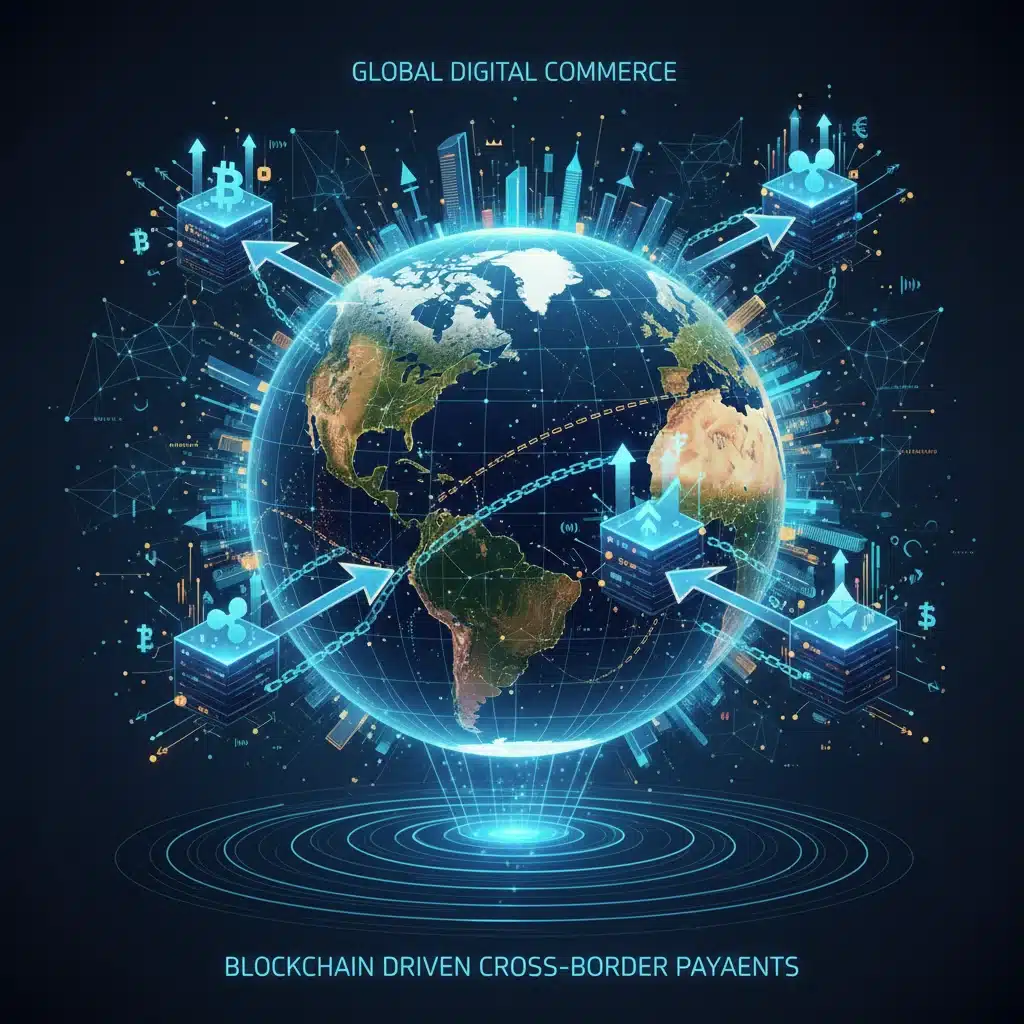
The third pivotal global trend is the increasing integration of digital currencies into cross-border payments and trade finance. Traditional international payment systems are often slow, expensive, and opaque, particularly for smaller transactions or remittances. Digital currencies offer the promise of instant, low-cost, and transparent transfers, potentially revolutionizing how businesses and individuals conduct international commerce. This trend has significant implications for U.S. economic stability, particularly concerning trade competitiveness and the efficiency of global supply chains.
Remittances and Financial Inclusion
One of the earliest and most impactful applications of digital currencies has been in remittances. Migrant workers sending money home often face exorbitant fees and long transfer times through traditional channels. Cryptocurrencies and stablecoins, particularly those pegged to stable assets, offer a faster and cheaper alternative. As more countries and individuals adopt these methods, the flow of capital becomes more efficient, directly benefiting recipient economies and potentially increasing their purchasing power for U.S. goods and services.
Furthermore, digital currencies can foster greater financial inclusion globally. For populations without access to traditional banking services, a smartphone and an an internet connection can unlock participation in the digital economy. This widespread access, particularly in developing nations, can stimulate economic growth and create new markets, indirectly benefiting U.S. businesses and investment opportunities.
Trade Finance and Supply Chain Efficiency
Beyond remittances, digital currencies and blockchain technology are poised to transform trade finance. The complex and paper-intensive nature of international trade often leads to delays, fraud, and high costs. Blockchain-based solutions can streamline processes, provide immutable records of transactions, and enable smart contracts to automate payments upon fulfillment of conditions. This can significantly reduce the risk and cost associated with international trade, making it more accessible for small and medium-sized enterprises (SMEs).
For the U.S., embracing these innovations could enhance the competitiveness of its exports and improve the efficiency of its global supply chains. If U.S. businesses can leverage digital currencies for faster and cheaper international payments, they can operate more efficiently and potentially gain a competitive edge. Conversely, if the U.S. banking sector and regulatory framework fail to adapt, American companies might find themselves at a disadvantage compared to international competitors operating with more agile digital payment infrastructures.
Geopolitical and Economic Implications
The integration of digital currencies into cross-border payments also has geopolitical ramifications. As mentioned earlier, alternative payment rails could reduce reliance on the U.S.-dominated SWIFT system, potentially impacting the effectiveness of U.S. sanctions. While this presents a challenge, it also compels the U.S. to innovate and ensure that its own financial infrastructure remains competitive and attractive for global commerce. The digital currency impact on global trade flows is a double-edged sword, offering both risks and opportunities for U.S. economic stability.
Navigating the Future: U.S. Policy and Strategic Adaptations
The three global trends – the CBDC race, the maturation of DeFi and cryptocurrencies under regulatory scrutiny, and the integration of digital currencies into cross-border payments – are not isolated phenomena. They are interconnected and collectively will exert significant pressure on U.S. economic stability by 2026. The U.S. government, its financial institutions, and businesses must adopt proactive and strategic approaches to navigate this evolving landscape.
Policy Cohesion and Innovation
One of the primary challenges for the U.S. is to develop a cohesive and forward-looking policy framework for digital assets. This requires greater coordination among federal agencies, clear legislative guidance from Congress, and a willingness to adapt existing regulations to new financial technologies. A balanced approach that fosters innovation while mitigating risks is essential. This includes exploring the benefits of a digital dollar, establishing clear rules for stablecoins, and creating a robust regulatory sandbox for emerging blockchain technologies.
Furthermore, the U.S. must continue to invest in research and development in blockchain and digital ledger technologies. Maintaining technological leadership is crucial for shaping global standards and ensuring that American companies remain at the forefront of this financial revolution. This isn’t just about competing with China or other nations; it’s about ensuring that the U.S. continues to drive innovation that benefits its economy and citizens.
International Collaboration and Standard Setting
Given the inherently global nature of digital currencies, international collaboration is paramount. The U.S. should actively engage with international bodies like the G7, G20, IMF, and FSB to develop common standards and best practices for digital asset regulation, cybersecurity, and interoperability. Harmonized regulations can prevent regulatory arbitrage, enhance financial stability, and facilitate legitimate cross-border digital currency flows. The goal should be to shape a global digital financial system that aligns with U.S. values of transparency, rule of law, and fair competition.
Education and Workforce Development
Finally, preparing the U.S. workforce and public for the digital currency future is crucial. This involves enhancing financial literacy regarding digital assets, educating consumers about the risks and benefits, and investing in STEM education to develop a skilled workforce capable of building and managing the next generation of financial infrastructure. A digitally literate populace and a skilled workforce will be better equipped to leverage the opportunities presented by digital currencies and adapt to the changes they bring.
Conclusion: The Imperative of Adaptation for U.S. Economic Stability
The rise of digital currencies is not merely a technological fad; it represents a fundamental shift in the global financial paradigm. By 2026, the three global trends discussed – the CBDC race, the maturation and regulation of DeFi, and the integration into cross-border payments – will have significantly shaped the U.S. economic landscape. The digital currency impact will be felt across monetary policy, financial stability, trade competitiveness, and geopolitical influence.
For the U.S. to maintain its economic stability and global financial leadership, a proactive, strategic, and collaborative approach is essential. This means moving beyond cautious observation to active participation in shaping the future of digital finance. Embracing innovation, developing clear and consistent regulation, fostering international cooperation, and investing in human capital are not optional but imperative steps. The future of money is digital, and the future of U.S. economic stability hinges on its ability to effectively navigate this transformative journey.
The coming years will be a test of adaptability and foresight. Those who understand and strategically respond to the evolving digital currency landscape will be best positioned to thrive. The U.S. has a unique opportunity to lead in this new era, but only if it acts decisively and intelligently in response to these powerful global trends.