Navigating 2026 Inflation: US Strategies to Protect Your Purchasing Power by 10%
The economic landscape is in constant flux, and looking ahead to 2026, the specter of 2026 US inflation looms large for many American households and businesses. While predicting the future with absolute certainty is impossible, understanding potential inflationary pressures and developing proactive strategies can be the key to not just surviving, but thriving. This comprehensive guide delves into the nuances of anticipated 2026 US inflation, offering actionable insights and robust strategies designed to help you protect and even grow your purchasing power by a significant 10%.
Inflation, at its core, is the rate at which the general level of prices for goods and services is rising, and subsequently, purchasing power is falling. A moderate level of inflation is often seen as a sign of a healthy, growing economy. However, when inflation accelerates beyond a comfortable range, it can erode savings, increase living costs, and create significant financial instability. As we approach 2026, several factors could contribute to an inflationary environment in the United States, making it crucial for individuals and businesses alike to be prepared.
The goal of this article is not to instill panic, but rather to empower you with knowledge and practical steps. We will explore the potential drivers of 2026 US inflation, analyze its historical context, and most importantly, equip you with a toolkit of financial strategies. From smart investment choices to astute budgeting and diversification, we aim to provide a roadmap that enables you to maintain, and ideally enhance, your financial well-being in the face of rising prices.
Understanding the Drivers of 2026 US Inflation
To effectively combat 2026 US inflation, we must first understand what might fuel it. Several macroeconomic factors could converge to create an inflationary environment:
Supply Chain Disruptions
Even after recent challenges, global supply chains remain fragile. Geopolitical tensions, natural disasters, or unexpected demand surges can still lead to bottlenecks, driving up the cost of raw materials and finished goods. If these disruptions persist or re-emerge more severely by 2026, they will undoubtedly contribute to higher prices for consumers and businesses.
Fiscal and Monetary Policies
Government spending and central bank policies play a pivotal role. Significant government stimulus packages, while beneficial in times of crisis, can inject large amounts of money into the economy, potentially leading to ‘too much money chasing too few goods.’ Similarly, sustained low interest rates by the Federal Reserve can encourage borrowing and spending, further stimulating demand and contributing to inflationary pressures. Monitoring these policy decisions will be crucial for anticipating 2026 US inflation.
Wage-Price Spiral
A classic inflationary scenario involves a wage-price spiral. As the cost of living increases due to inflation, workers demand higher wages to maintain their purchasing power. Businesses, facing higher labor costs, then raise prices for their products and services, which in turn fuels further wage demands. This cycle can be difficult to break once established and is a key concern when discussing potential 2026 US inflation.
Energy Prices and Geopolitics
Energy costs are a fundamental component of nearly every good and service. Fluctuations in global oil and gas prices, often driven by geopolitical events, can have a cascading effect across the economy, pushing up transportation costs, manufacturing expenses, and ultimately consumer prices. Any significant instability in energy-producing regions could be a major driver of inflation by 2026.
Demand-Side Pressures
A robust economy with strong consumer demand can also lead to inflation. If consumers have ample savings and a strong desire to spend, businesses may find it easier to raise prices without losing customers. This ‘demand-pull’ inflation is often a sign of economic strength but can become problematic if it outpaces supply growth.
Historical Context: Lessons from Past Inflationary Periods
Understanding the historical performance of different assets and strategies during inflationary periods can provide valuable insights for navigating 2026 US inflation. The 1970s, for example, serve as a stark reminder of the challenges posed by persistent, high inflation. During this decade, the US experienced stagflation – a period of high inflation combined with slow economic growth and high unemployment.
Key takeaways from historical inflation events include:
- Real Assets Tend to Perform Well: Commodities, real estate, and certain types of stocks (especially those of companies with pricing power) have historically acted as hedges against inflation.
- Fixed-Income Vulnerability: Bonds and other fixed-income investments can suffer significantly as inflation erodes the real value of their fixed payments.
- Importance of Diversification: A diversified portfolio, spread across various asset classes, is crucial to mitigate risks during uncertain economic times.
- Cash Erosion: Holding large amounts of cash can be detrimental as its purchasing power diminishes rapidly.
By studying these patterns, we can better position ourselves to develop effective strategies for 2026 US inflation.
Strategy 1: Smart Investing to Outpace 2026 US Inflation
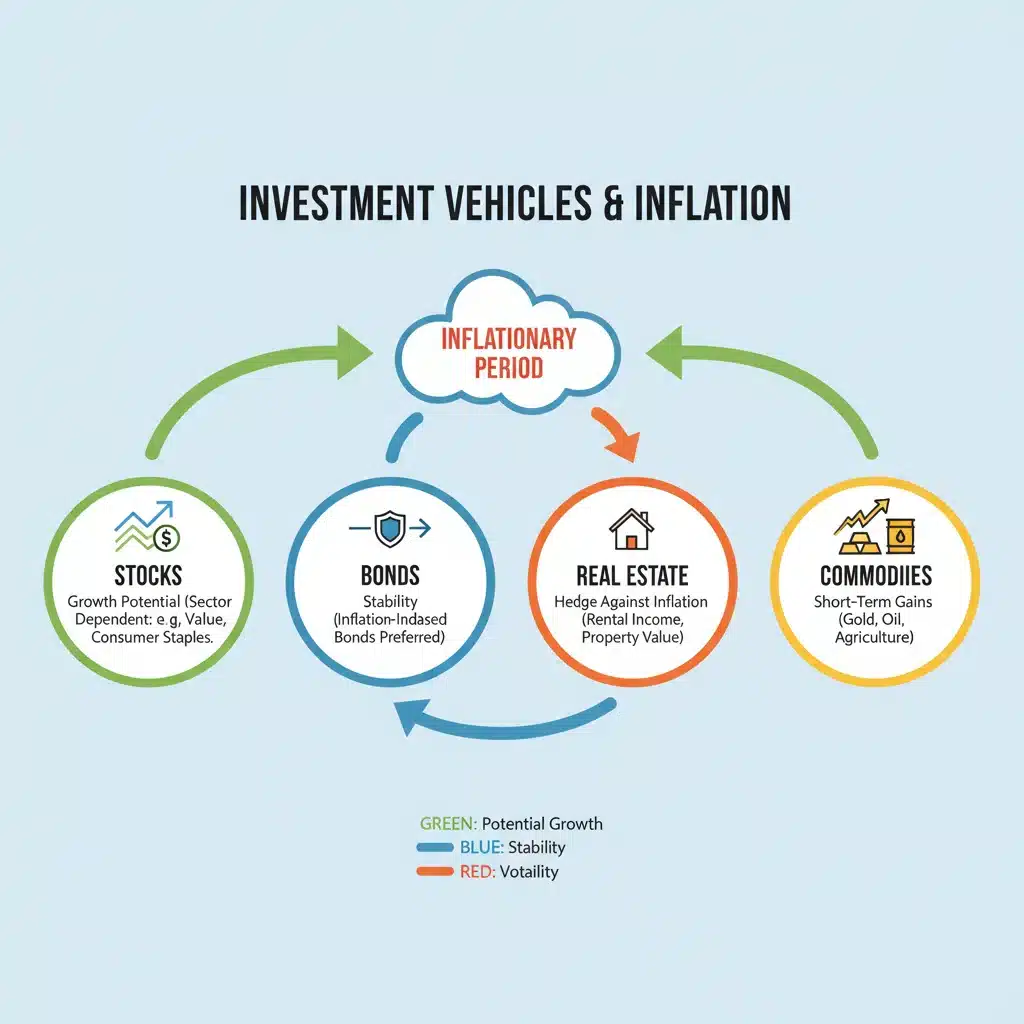
Investing wisely is perhaps the most powerful tool for protecting and growing your purchasing power. The goal is to select assets that historically perform well or offer a hedge against rising prices. Aiming for a 10% increase in purchasing power requires a multi-faceted approach.
Real Estate Investments
Real estate has traditionally been an excellent inflation hedge. Property values and rental income often increase with inflation, providing a natural buffer against rising costs. Consider:
- Direct Property Ownership: Residential or commercial properties can provide rental income that adjusts with inflation and capital appreciation.
- Real Estate Investment Trusts (REITs): These are companies that own, operate, or finance income-generating real estate. They offer a way to invest in real estate without directly owning physical property, providing liquidity and diversification.
When evaluating real estate, focus on properties in growing areas with strong demand, as these are more likely to see sustained appreciation and rental growth, crucial for combating 2026 US inflation.
Commodities and Precious Metals
Commodities like oil, gas, agricultural products, and industrial metals often see their prices rise during inflationary periods because they are the raw materials for goods and services. Precious metals, particularly gold and silver, are also considered traditional inflation hedges and safe-haven assets.
- Gold: Often seen as a store of value, gold tends to perform well when confidence in fiat currencies wanes or inflation fears rise.
- Broad Commodity ETFs/Funds: These allow you to invest in a basket of commodities, providing diversification and reducing risk compared to investing in a single commodity.
These assets can act as a counterbalance to traditional financial instruments during periods of high 2026 US inflation.
Inflation-Protected Securities (TIPS)
Treasury Inflation-Protected Securities (TIPS) are US Treasury bonds that are indexed to inflation to protect investors from the erosion of purchasing power. The principal value of TIPS adjusts with changes in the Consumer Price Index (CPI). When inflation rises, the principal value of TIPS increases, and vice versa. This means both the interest payments and the final principal repayment are adjusted for inflation, making them a direct hedge against 2026 US inflation.
Stocks of Companies with Pricing Power
Not all stocks are equal during inflationary times. Focus on companies that have strong pricing power – the ability to raise their prices without significant loss of sales volume. These often include:
- Essential Goods and Services: Companies providing necessities (e.g., utilities, consumer staples) often have inelastic demand, allowing them to pass on higher costs.
- Strong Brands/Monopolies: Companies with dominant market positions or unique products can maintain their margins even as input costs rise.
- Low Debt Companies: High debt can become a burden when interest rates rise in response to inflation.
Careful selection of equities can be a powerful strategy against 2026 US inflation.
Strategy 2: Budgeting and Expense Management to Counter 2026 US Inflation
While investing helps grow your money, prudent budgeting and expense management are critical for preventing your existing purchasing power from eroding. This strategy is about optimizing your spending habits to get more out of every dollar, effectively increasing your purchasing power by reducing unnecessary expenditures.
Re-evaluate Your Budget
In an inflationary environment, a static budget is a failing budget. You need to regularly review and adjust your spending plan. Categorize your expenses into needs and wants. Identify areas where you can cut back without significantly impacting your quality of life. This could include:
- Subscription Services: Cancel unused streaming services, gym memberships, or software subscriptions.
- Discretionary Spending: Reduce dining out, entertainment, and non-essential purchases.
- Transportation: Explore carpooling, public transport, or more fuel-efficient driving habits.
Every dollar saved is a dollar whose purchasing power you’ve preserved against 2026 US inflation.
Negotiate and Shop Smart
Don’t be afraid to negotiate for better prices on services like internet, cable, and insurance. Always compare prices before making significant purchases. Utilize sales, coupons, and loyalty programs. Buying in bulk for non-perishable items when prices are favorable can also lock in lower costs.
Reduce Debt, Especially Variable-Rate Debt
As inflation rises, central banks often raise interest rates to cool the economy. This makes variable-rate debt (like credit card balances or adjustable-rate mortgages) more expensive. Prioritizing the payoff of high-interest debt can save you a significant amount in interest payments, effectively freeing up more of your income to combat 2026 US inflation.
Increase Income Streams
One of the most direct ways to increase your purchasing power is to increase your income. This could involve:
- Asking for a Raise: If your skills are in demand and you’ve been a valuable employee, negotiate a salary increase that at least keeps pace with inflation.
- Side Hustles: Explore opportunities to generate additional income through freelancing, consulting, or part-time work.
- Skill Development: Invest in learning new skills that are highly valued in the job market, potentially opening doors to higher-paying roles.
Boosting your income directly counteracts the erosive effects of 2026 US inflation.
Strategy 3: Diversification and Risk Management
Diversification is not just about spreading your investments; it’s about building resilience into your entire financial plan. A well-diversified approach minimizes exposure to any single point of failure and enhances your ability to weather economic storms, including 2026 US inflation.
Geographic Diversification
Consider diversifying your investments beyond the US market. While 2026 US inflation is our primary focus, other economies might perform differently. Investing in international stocks or global funds can provide a hedge if the US economy faces particular challenges.
Sector Diversification
Within equities, ensure your portfolio isn’t overly concentrated in one or two sectors. While some sectors may thrive during inflation (e.g., energy, materials), others might struggle. A balanced approach across various industries can reduce overall risk.
Alternative Investments
Beyond traditional stocks, bonds, and real estate, explore alternative investments that may behave differently during inflationary periods. These can include:
- Private Equity: Investing in private companies can offer different risk/reward profiles.
- Hedge Funds: Some hedge funds employ strategies specifically designed to profit from market volatility or inflation.
- Collectibles/Art: While not for everyone, certain high-value collectibles can appreciate during inflation, though they come with their own risks and lack liquidity.
It’s important to thoroughly research and understand the risks associated with any alternative investment before committing capital, especially when preparing for 2026 US inflation.
Strategy 4: Education and Continuous Monitoring
The economic environment is dynamic. What works today might not be optimal tomorrow. Therefore, continuous education and monitoring are paramount for effectively navigating 2026 US inflation and beyond.
Stay Informed
Regularly follow economic news, reports from central banks (like the Federal Reserve), and analyses from reputable financial institutions. Understand key economic indicators such as the Consumer Price Index (CPI), Producer Price Index (PPI), and employment figures. This knowledge will help you anticipate shifts and adjust your strategies proactively.
Review Your Financial Plan Regularly
Your financial plan should not be a static document. Schedule regular reviews (at least annually, or more frequently if economic conditions are volatile) to assess whether your investments and budget are still aligned with your goals and the prevailing economic climate. Adjust your asset allocation, savings rate, and spending as needed to maintain your 10% purchasing power protection target against 2026 US inflation.
Seek Professional Advice
Consider consulting with a qualified financial advisor. They can provide personalized guidance based on your specific financial situation, risk tolerance, and goals. A good advisor can help you construct a resilient portfolio and develop a comprehensive plan to navigate the complexities of 2026 US inflation.
Practical Steps to Implement Your 2026 US Inflation Strategy
Moving from theory to action is crucial. Here’s a checklist of practical steps you can take:
- Assess Your Current Financial Situation: Understand your net worth, income, expenses, and existing investments.
- Define Your Inflation Protection Goal: Clearly state your objective, e.g., ‘to protect 10% of my purchasing power against 2026 US inflation.’
- Optimize Your Budget: Identify and eliminate unnecessary expenses. Create a lean, efficient spending plan.
- Build an Emergency Fund: Ensure you have 3-6 months of living expenses saved in an accessible, interest-bearing account.
- Review Your Investment Portfolio: Rebalance your portfolio to include inflation-hedging assets like real estate, commodities, TIPS, and strong-performing stocks.
- Pay Down High-Interest Debt: Reduce your exposure to variable-rate loans and credit card debt.
- Explore Income Augmentation: Look for ways to increase your earnings, whether through a raise, a side hustle, or skill development.
- Stay Informed and Adapt: Continuously monitor economic indicators and be prepared to adjust your strategies as needed.
- Consult a Financial Professional: Get expert, personalized advice to refine your plan.
The Long-Term View Beyond 2026 US Inflation
While our focus is on 2026 US inflation, it’s important to adopt a long-term perspective. Inflation is a recurring economic phenomenon, and the strategies you implement now will serve you well in future inflationary cycles. Building financial discipline, a diversified portfolio, and a habit of continuous learning are assets that appreciate over time, regardless of the immediate economic climate.
Protecting your purchasing power by 10% against 2026 US inflation is an ambitious yet achievable goal. It requires diligence, strategic planning, and a willingness to adapt. By taking proactive steps today, you can position yourself for greater financial security and peace of mind in the years to come.
The journey to financial resilience against inflation is ongoing. It’s about making informed decisions, being disciplined with your resources, and consistently optimizing your approach. Don’t let the fear of future inflation paralyze you; instead, let it motivate you to take control of your financial destiny.
Remember, your financial health is a marathon, not a sprint. The strategies outlined here are designed to build a robust foundation that can withstand the pressures of 2026 US inflation and future economic challenges. Start today, stay consistent, and watch your purchasing power strengthen.