Breaking: New Federal Housing Initiatives for 2026 Aim to Reduce Costs by 10% for First-Time Buyers. (RECENT UPDATES)
The dream of homeownership, long considered a cornerstone of the American ideal, has become increasingly elusive for many, especially first-time buyers. Skyrocketing home prices, rising interest rates, and a competitive market have created significant barriers. However, a beacon of hope is on the horizon with the announcement of new federal housing initiatives slated for 2026, designed to significantly alleviate these burdens. These groundbreaking programs aim to reduce housing costs by an ambitious 10% for eligible first-time homebuyers, marking a pivotal moment in the nation’s ongoing efforts to foster affordable and accessible housing.
This comprehensive article delves into the specifics of these upcoming federal housing initiatives, exploring their core components, eligibility criteria, and the anticipated impact on the housing market and prospective homeowners. We will also provide recent updates and expert insights to help you navigate this evolving landscape and prepare for the opportunities that lie ahead.
Understanding the Landscape: Why New Federal Housing Initiatives Are Crucial
Before diving into the specifics of the 2026 initiatives, it’s essential to understand the current challenges facing first-time homebuyers. The housing market has been characterized by:
- Unprecedented Price Growth: Over the past decade, home values have surged, far outpacing wage growth in many regions. This makes saving for a down payment a monumental task.
- Limited Inventory: A persistent shortage of available homes, particularly in the affordable segment, has fueled bidding wars and driven prices even higher.
- Rising Interest Rates: While rates fluctuate, recent increases have added thousands of dollars to monthly mortgage payments, further stretching budgets.
- Student Loan Debt: Many potential first-time buyers are burdened by substantial student loan debt, which impacts their debt-to-income ratio and ability to qualify for mortgages.
- Inflationary Pressures: General inflation has eroded purchasing power, making it harder for individuals and families to save for a home.
These factors collectively paint a challenging picture for those aspiring to own their first home. Recognizing these systemic issues, the federal government has committed to implementing robust solutions, culminating in the 2026 federal housing initiatives. These initiatives are not merely incremental adjustments; they represent a strategic and multi-faceted approach to fundamentally improve housing affordability.
Key Pillars of the 2026 Federal Housing Initiatives
The proposed federal housing initiatives are built upon several key pillars, each designed to address specific barriers to homeownership. While full details are still being finalized, preliminary announcements highlight the following core components:
1. Enhanced Down Payment Assistance Programs
One of the most significant hurdles for first-time buyers is accumulating a sufficient down payment. Many conventional loans require 20% down to avoid private mortgage insurance (PMI), which can amount to tens of thousands of dollars. The 2026 initiatives are expected to introduce or significantly expand federal down payment assistance programs. These could include:
- Grants and Forgivable Loans: Direct financial aid that does not need to be repaid, or loans that are forgiven after a certain period of occupancy.
- Increased Loan-to-Value (LTV) Ratios: Allowing buyers to secure mortgages with lower down payments, potentially as little as 3% or even 0% for specific programs, while still benefiting from favorable terms.
- Streamlined Application Processes: Reducing the bureaucratic burden associated with applying for assistance, making it more accessible to a broader range of eligible buyers.
The goal here is to reduce the upfront financial burden, enabling more individuals to transition from renting to owning without years of arduous saving.
2. Mortgage Interest Rate Subsidies and Tax Credits
Beyond the down payment, the monthly mortgage payment is a primary concern. The new federal housing initiatives are exploring mechanisms to reduce the effective interest rate for first-time buyers. This could manifest as:
- Direct Interest Rate Subsidies: Government payments to lenders to effectively lower the interest rate for eligible borrowers for the initial years of the loan.
- Expanded Mortgage Interest Tax Credits: Enhancing existing tax credits or introducing new ones that directly reduce a homeowner’s tax liability, effectively lowering the overall cost of their mortgage.
- Flexible Mortgage Products: Encouraging lenders to offer more flexible mortgage products tailored to first-time buyers, such as graduated payment mortgages where payments start lower and increase over time as income is expected to grow.
These measures aim to make monthly housing costs more manageable, thereby improving affordability over the long term.
3. Initiatives for Affordable Housing Supply
Addressing the demand side without tackling the supply shortage would only offer temporary relief. Therefore, a crucial element of the 2026 federal housing initiatives involves bolstering the supply of affordable housing. This includes:
- Incentives for Developers: Providing tax breaks, grants, and streamlined permitting processes for developers who build affordable housing units, especially those targeting first-time buyers.
- Conversion Programs: Funding programs that convert underutilized commercial properties or vacant land into residential housing.
- Modular and Manufactured Housing Support: Promoting the use of innovative construction methods like modular and manufactured homes, which can significantly reduce construction costs and time.
- Community Land Trusts Expansion: Supporting the growth of community land trusts, which aim to keep housing permanently affordable by separating land ownership from home ownership.
By increasing the overall availability of housing, particularly at lower price points, the initiatives seek to naturally ease market pressures and contribute to a 10% cost reduction.
4. Credit Repair and Homebuyer Education Programs
Many potential first-time buyers face challenges with credit scores or lack the financial literacy needed to navigate the home-buying process. The 2026 federal housing initiatives recognize this and are expected to include:
- Enhanced Credit Counseling Services: Federally funded programs offering free or low-cost credit counseling to help individuals improve their credit scores.
- Mandatory Homebuyer Education: Providing comprehensive educational resources on budgeting, mortgage types, the closing process, and homeowner responsibilities. This empowers buyers to make informed decisions and avoid common pitfalls.
- Pre-purchase Advising: Offering personalized guidance from certified housing counselors to help buyers prepare for homeownership.
These supportive services are vital for ensuring that first-time buyers are not only able to purchase a home but are also prepared for the responsibilities of homeownership, thereby promoting long-term success.
Who Benefits? Eligibility for the 2026 Initiatives
While the precise eligibility requirements for each specific program under the 2026 federal housing initiatives will vary, general criteria for ‘first-time homebuyers’ and income limits are expected to be central. Typically, a first-time homebuyer is defined as someone who has not owned a primary residence in the past three years. Income limits will likely be set as a percentage of the Area Median Income (AMI), ensuring that the benefits are directed towards those who need them most.
Potential eligibility factors may include:
- Income Thresholds: Capping eligibility at a certain percentage of the AMI (e.g., 80% or 120% of AMI) for the specific area.
- First-Time Homebuyer Status: As defined above, often with exceptions for single parents or individuals displaced due to natural disasters.
- Property Type Restrictions: Some programs might focus on specific property types, such as single-family homes, condominiums, or even multi-family properties where the buyer occupies one unit.
- Location-Based Incentives: Certain initiatives might offer enhanced benefits for purchasing homes in designated underserved or revitalizing communities.
- Credit Score Requirements: While some programs might have flexible credit score requirements, others may still necessitate a minimum score, though often lower than conventional loans.
Prospective buyers are strongly encouraged to begin gathering financial documents, reviewing their credit reports, and researching their local AMI to understand their potential eligibility once the full details are released.
Anticipated Impact: A 10% Reduction in Housing Costs
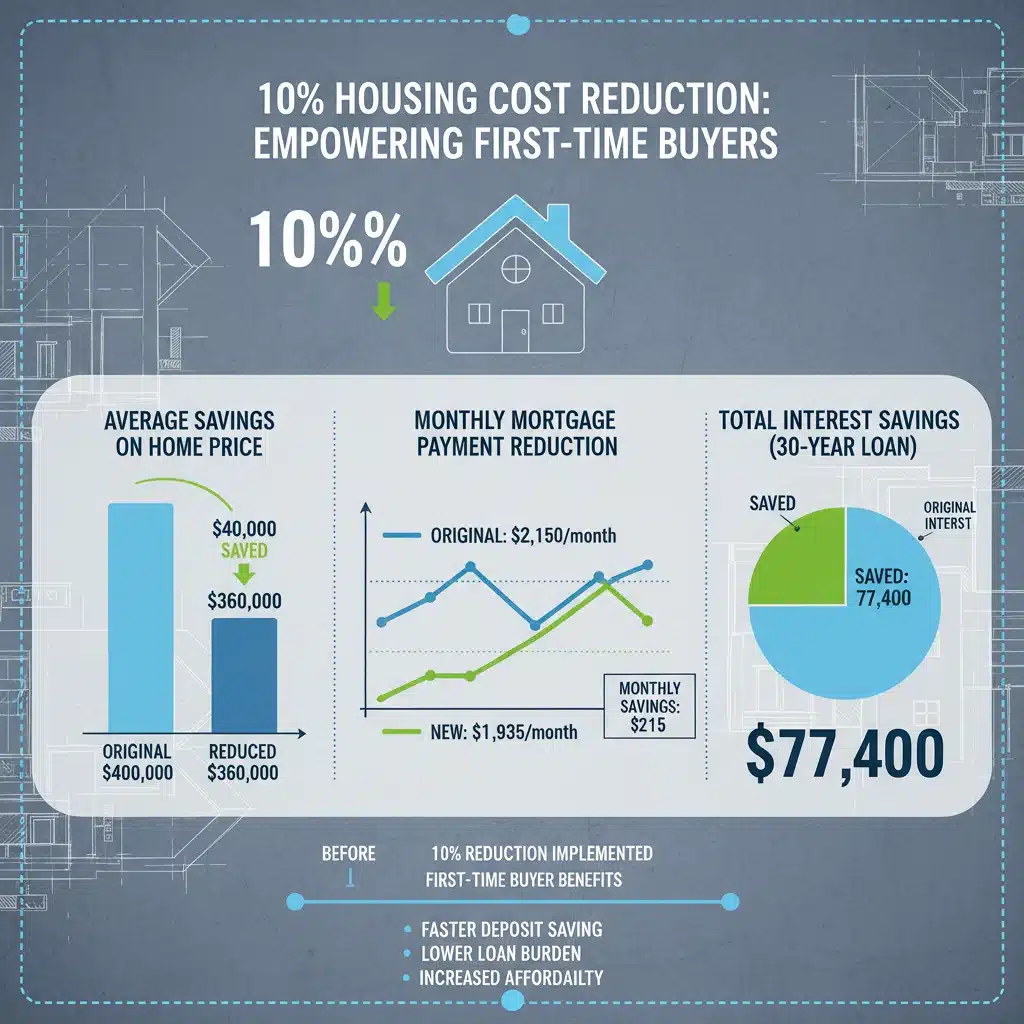
The headline promise of these federal housing initiatives is a 10% reduction in housing costs for first-time buyers. This isn’t just a marketing slogan; it’s a carefully calculated target based on the combined effect of the various programs. This reduction could manifest in several ways:
- Lower Purchase Price: Through supply-side interventions and incentives for developers, the overall cost of entry-level homes could decrease or at least stabilize.
- Reduced Upfront Costs: Significant down payment assistance means less money out-of-pocket at closing.
- Lower Monthly Payments: Interest rate subsidies or tax credits will directly translate to more affordable monthly mortgage payments.
- Decreased Ancillary Costs: Some initiatives might also target closing costs, appraisal fees, or other expenses associated with home buying.
To illustrate, consider a home priced at $300,000. A 10% reduction could mean a saving of $30,000, either directly off the purchase price, through reduced interest over the life of the loan, or via substantial down payment assistance. This figure could be the difference between renting and owning for many families.
Economic Ripple Effects
Beyond individual buyers, the 2026 federal housing initiatives are expected to have broader economic impacts:
- Stimulating Local Economies: Increased home sales lead to more activity in related industries like construction, real estate, and home improvement.
- Wealth Creation: Homeownership is a primary driver of intergenerational wealth. By making it more accessible, these initiatives can help reduce wealth inequality.
- Community Stabilization: Higher rates of homeownership often correlate with more stable communities, increased civic engagement, and better educational outcomes.
- Addressing Housing Shortages: The supply-side interventions are crucial for alleviating the chronic housing shortages that plague many parts of the country.
While some critics might raise concerns about potential market distortions or inflation, proponents argue that the targeted nature of these programs, coupled with supply-side interventions, is designed to mitigate such risks and achieve sustainable affordability.
Recent Updates and What to Expect Next
As 2026 approaches, more detailed information regarding the federal housing initiatives will undoubtedly emerge. Here are some recent updates and what prospective buyers should keep an eye on:
- Legislative Progress: Key legislation supporting these initiatives is moving through Congress, with bipartisan support for addressing housing affordability. Specific bills are being debated that outline funding mechanisms and administrative structures.
- Agency Collaboration: Various federal agencies, including HUD, Fannie Mae, and Freddie Mac, are coordinating their efforts to ensure a unified and effective rollout of the programs. This collaboration is crucial for seamless implementation.
- Pilot Programs: Some smaller-scale pilot programs are already being tested in select regions, providing valuable data and insights that will inform the broader 2026 rollout. These pilots are helping refine eligibility criteria and delivery mechanisms.
- Public Information Campaigns: Expect extensive public information campaigns closer to the launch date to educate potential homebuyers and housing professionals about the new opportunities.
It is vital for interested parties to remain vigilant for official announcements from government agencies and reputable housing organizations. Subscribing to newsletters from HUD, local housing authorities, and accredited non-profits can be an excellent way to stay informed.
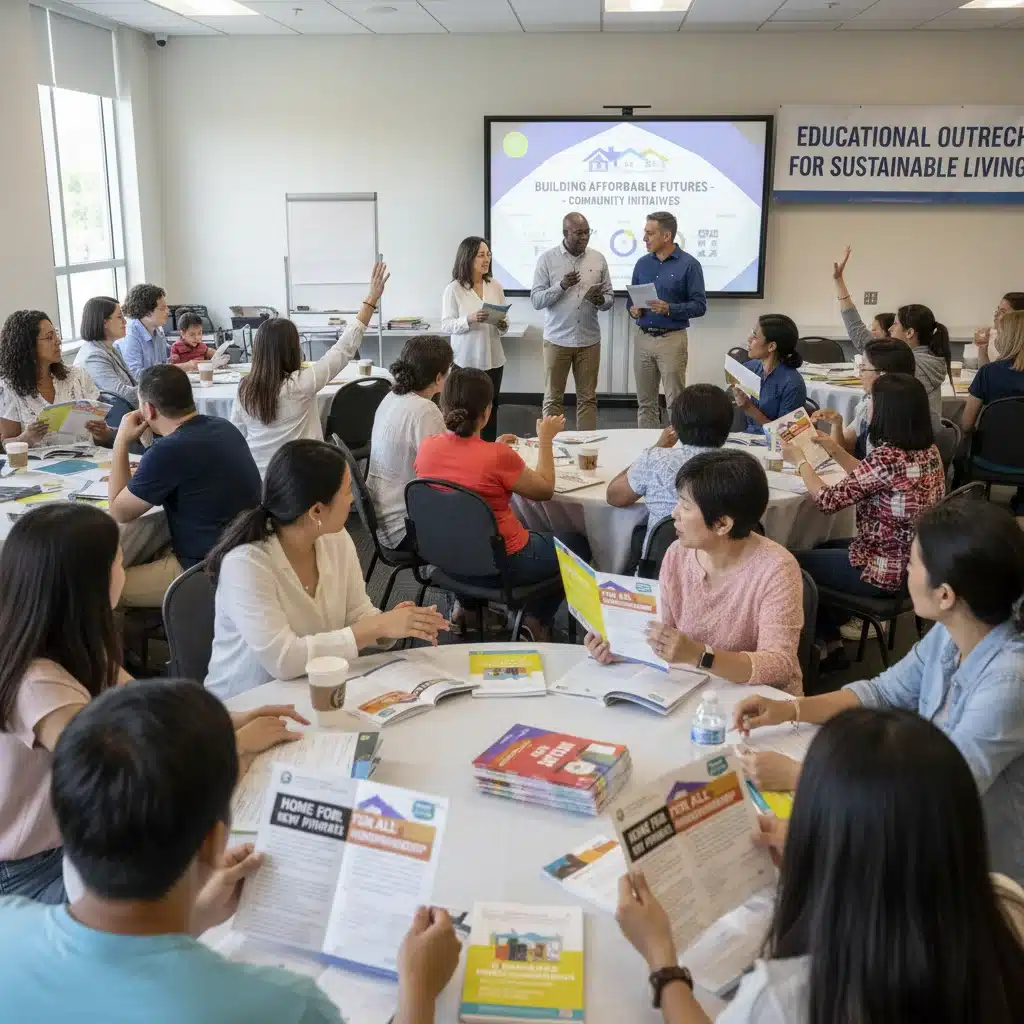
Preparing for the 2026 Federal Housing Initiatives
Even though 2026 is still some time away, there are proactive steps first-time homebuyers can take now to position themselves advantageously for these upcoming federal housing initiatives:
1. Improve Your Credit Score
A good credit score is fundamental to securing favorable mortgage terms. Start by obtaining your free annual credit reports from AnnualCreditReport.com. Review them for errors and dispute any inaccuracies. Focus on paying bills on time, reducing credit card debt, and avoiding opening new lines of credit unnecessarily. A higher credit score will open up more opportunities and potentially better interest rates, even with subsidies.
2. Save Aggressively
While the initiatives aim to reduce upfront costs, having some savings is always beneficial. A personal emergency fund, even a small one, provides a buffer against unexpected expenses. The more you can save, the less reliant you’ll be on assistance programs, and the more financial flexibility you’ll have. Even with a 10% cost reduction, there will still be closing costs and moving expenses to consider.
3. Research Local Housing Markets
Understand the dynamics of the housing market in areas where you wish to buy. Look at average home prices, property taxes, and the availability of homes within your target budget. This local knowledge will be invaluable when the 2026 programs roll out, as some initiatives might be geographically targeted or offer varying benefits based on regional needs.
4. Attend Homebuyer Education Courses
Many non-profit organizations and HUD-approved counseling agencies offer free or low-cost homebuyer education courses. These courses provide essential knowledge about the home-buying process, budgeting, mortgage types, and homeowner responsibilities. Completing such a course might even become a prerequisite for some of the 2026 federal housing initiatives.
5. Consult with a Housing Counselor
A certified housing counselor can provide personalized advice based on your financial situation. They can help you understand current programs, prepare for future ones, and develop a realistic homeownership plan. Their expertise can be a critical asset in navigating the complexities of the housing market.
6. Understand Your Debt-to-Income Ratio
Lenders use your debt-to-income (DTI) ratio to assess your ability to manage monthly mortgage payments. Aim to keep your DTI below 43%, though lower is always better. Work on reducing existing debts, especially high-interest credit card debt, to improve this ratio.
Potential Challenges and Considerations
While the 2026 federal housing initiatives offer immense promise, it’s also important to consider potential challenges:
- Demand Surge: A significant reduction in costs could lead to an immediate surge in demand, potentially offsetting some of the intended price relief if supply doesn’t keep pace.
- Program Complexity: Multiple programs with varying eligibility criteria can be confusing for applicants. Clear communication and streamlined processes will be crucial.
- Funding Durability: The long-term success of these initiatives will depend on sustained federal funding and political will.
- Regional Disparities: While national in scope, the impact of these initiatives may vary significantly across different regions due to local market conditions and housing policies.
Policymakers will need to carefully monitor these factors and remain agile in adjusting the programs to ensure they achieve their intended goals effectively and equitably.
Conclusion: A New Era for First-Time Homebuyers
The upcoming 2026 federal housing initiatives represent a significant commitment to making the American dream of homeownership a reality for more citizens. By targeting a 10% reduction in housing costs for first-time buyers through enhanced down payment assistance, interest rate subsidies, increased affordable housing supply, and robust educational programs, the government is laying the groundwork for a more equitable and accessible housing market.
While the full details are still unfolding, the overarching goal is clear: to dismantle the financial barriers that have kept many aspiring homeowners on the sidelines. For those dreaming of purchasing their first home, these initiatives offer a powerful reason for optimism. By taking proactive steps now – improving credit, saving diligently, and educating oneself – prospective buyers can position themselves to fully leverage these transformative programs. The future of homeownership in America is poised for a significant and positive shift, and these federal housing initiatives are at the forefront of that change.