US Trade Policies 2026: Impact on Domestic Manufacturing
The Impact of New US Trade Policies on Domestic Manufacturing: Q1 2026 Analysis
The landscape of global trade is in a constant state of flux, and the United States, as a major economic powerhouse, often sets the tone for these shifts. As we delve into the first quarter of 2026, a series of new US trade policies have begun to unfurl their effects, particularly on the domestic manufacturing sector. Understanding the nuances of these policies and their comprehensive impact is crucial for businesses, policymakers, and consumers alike. This article provides an in-depth analysis of how these recent trade decisions are reshaping American industries, fostering both opportunities and challenges within the nation’s manufacturing base.
The Biden administration, building on previous frameworks and introducing its own strategic adjustments, has emphasized a dual approach: strengthening domestic production capabilities while recalibrating international trade relationships. This strategy is driven by a desire to enhance national security, create high-paying jobs, and address environmental concerns, all while navigating a complex geopolitical environment. The Q1 2026 period offers an initial glimpse into the practical implications of these ambitious goals, revealing how various sectors are adapting to the new economic realities.
From increased tariffs on specific imported goods to new incentives for ‘Made in America’ products, the policy toolkit is diverse. The overarching objective appears to be a revitalization of American industry, moving away from an over-reliance on foreign supply chains, particularly in critical sectors. However, such grand ambitions rarely come without complexities. The global interconnectedness of modern economies means that even well-intentioned domestic policies can send ripple effects across international markets, influencing everything from raw material costs to consumer prices.
This analysis will dissect the primary components of the new US trade policies, examining their direct and indirect consequences for domestic manufacturing. We will explore how these measures are influencing investment patterns, employment trends, technological adoption, and the overall competitiveness of American industries. By looking at specific examples and drawing on available data from the first quarter, we aim to provide a clear and comprehensive picture of the current situation and what it might portend for the future of US manufacturing.
Understanding the Core Tenets of New US Trade Policies
To fully grasp the impact on domestic manufacturing, it’s essential to first understand the foundational principles guiding the new US trade policies. These policies are not monolithic; rather, they represent a multifaceted approach designed to achieve several strategic objectives. At their core, these policies aim to bolster national economic security, promote fair trade practices, and stimulate job growth within the United States.
Tariffs and Trade Barriers: A Recalibrated Approach
One of the most visible components of the new trade agenda is the strategic application of tariffs and non-tariff barriers. Unlike previous administrations that sometimes employed broad-brush tariffs, the current approach in Q1 2026 appears more targeted, focusing on specific industries and countries deemed to engage in unfair trade practices or those critical for national security. For instance, increased duties have been observed on certain steel and aluminum products, advanced semiconductors, and electric vehicle components originating from particular regions. The rationale behind these tariffs is often twofold: to protect nascent or struggling domestic industries from cheaper foreign competition and to encourage reshoring or nearshoring of production facilities. The immediate effect on domestic manufacturers in these protected sectors can be a reduction in competitive pressure from imports, potentially leading to increased sales and production volumes. However, it also raises input costs for other domestic industries that rely on these imported materials, creating a complex web of economic winners and losers.
Incentives for Domestic Production and Innovation
Beyond punitive measures, the new trade policies also heavily lean on incentives to foster domestic manufacturing. These include tax credits for companies that invest in US-based production facilities, subsidies for research and development in critical technologies, and ‘Buy American’ provisions in government procurement contracts. The goal is to make it more economically attractive for companies to manufacture goods within the United States, thereby creating jobs and strengthening the industrial base. For Q1 2026, early indicators suggest a moderate uptick in domestic investment announcements, particularly in renewable energy, semiconductor fabrication, and advanced materials. These incentives are designed to not only bring production back but also to stimulate innovation and ensure the US remains at the forefront of technological advancement. The long-term success of these incentives will depend on their ability to create sustainable competitive advantages for US manufacturers, rather than just temporary boosts.
Strengthening Supply Chain Resilience
The vulnerabilities exposed during recent global crises have underscored the critical importance of resilient supply chains. A significant thrust of the new US trade policies in Q1 2026 is dedicated to de-risking and diversifying these chains. This involves encouraging manufacturers to source components and raw materials from a wider array of trusted partners, or ideally, from within the United States itself. Policies are being implemented to map critical supply chains, identify potential choke points, and provide support for companies willing to localize production of essential goods. For domestic manufacturers, this translates into increased pressure to evaluate their existing supply networks and explore new domestic sourcing options. While this can initially lead to higher costs or longer lead times as new relationships are forged, the long-term benefit is a more robust and less vulnerable manufacturing ecosystem, less susceptible to geopolitical shocks or natural disasters. This focus on resilience is a direct response to past disruptions and aims to future-proof US industries.
International Trade Agreements and Partnerships
Finally, the US trade strategy also involves a recalibration of international trade agreements and partnerships. While some past multilateral agreements are being re-evaluated, there’s a clear emphasis on forging new bilateral and minilateral agreements that align with US strategic interests. These agreements often include provisions related to labor standards, environmental protection, and intellectual property rights, aiming to create a level playing field for US manufacturers. The intent is to ensure that while the US promotes domestic production, it does so within a framework of fair and reciprocal trade with allies. For domestic manufacturers, these agreements can open new markets, reduce trade barriers for their exports, and protect them from unfair competition, provided the terms are favorable. The Q1 2026 period has seen ongoing negotiations and discussions, signaling a proactive diplomatic effort to shape the global trade architecture in a way that benefits American industries.
Initial Economic Indicators and Manufacturing Performance in Q1 2026
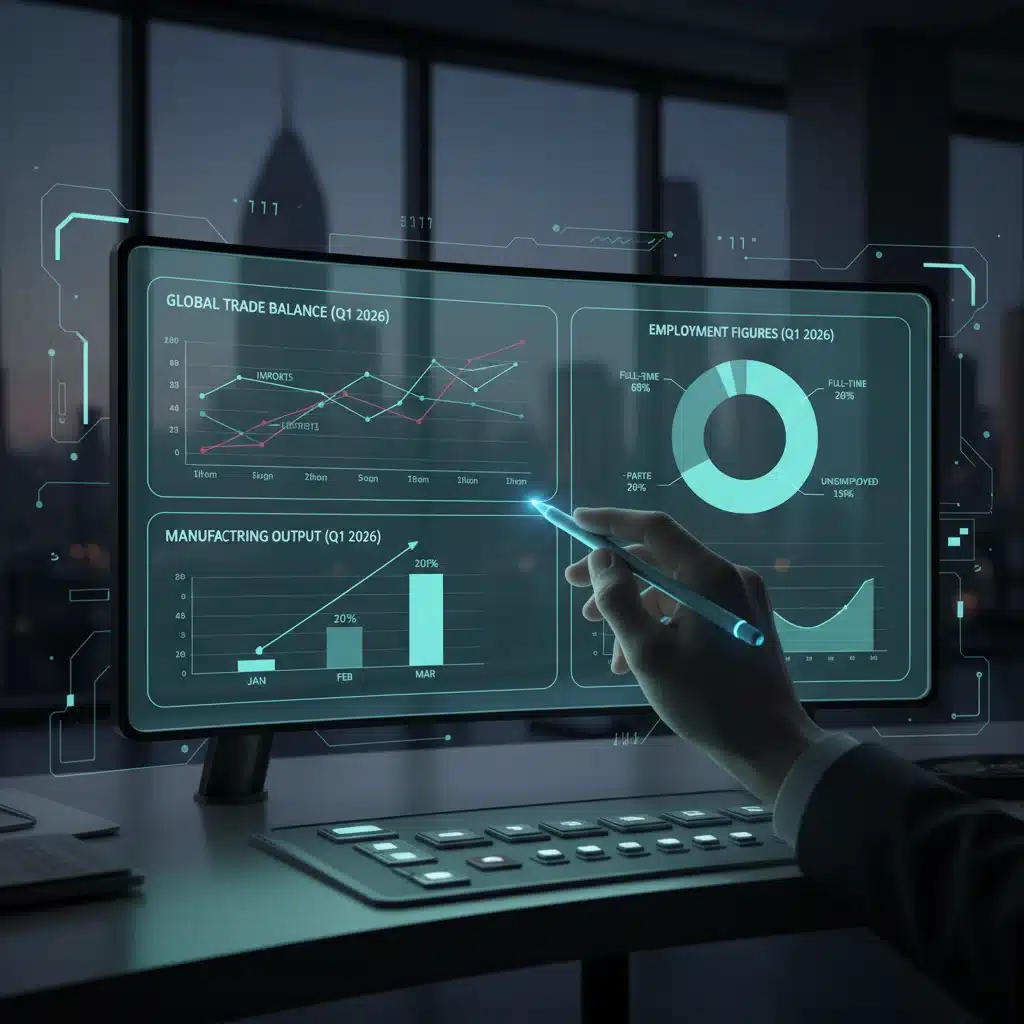
The first quarter of 2026 has provided a crucial initial look at how the new US trade policies are translating into tangible economic outcomes for domestic manufacturing. While it’s still early to draw definitive long-term conclusions, several key indicators offer valuable insights into the immediate effects and emerging trends. These indicators encompass manufacturing output, employment figures, capital investment, and shifts in specific industry sectors.
Manufacturing Output and Capacity Utilization
Overall manufacturing output in Q1 2026 has shown a mixed picture, reflecting the diverse impacts of the new policies. Sectors directly benefiting from increased tariffs on imports, such as certain basic metals and textiles, have reported modest increases in production. Domestic steel mills, for example, have seen a slight uptick in orders and capacity utilization, as foreign competition faces higher entry barriers. Conversely, industries heavily reliant on imported components that are now subject to higher duties have experienced increased production costs, which in some cases have translated into slower output growth or even slight declines as they adjust their supply chains. The overall manufacturing Purchasing Managers’ Index (PMI) has remained relatively stable, indicating resilience but also suggesting that the benefits in some areas are being offset by challenges in others. The data suggests that while the intention is to boost all domestic manufacturing, the reality on the ground is more nuanced, with some sectors adapting faster and more favorably than others.
Employment Trends in the Manufacturing Sector
Job creation within the manufacturing sector is a cornerstone of the new trade policies. In Q1 2026, preliminary employment data indicates a gradual but noticeable increase in manufacturing jobs, particularly in regions where new production facilities are being established or existing ones are expanding due to ‘reshoring’ initiatives. Industries like semiconductor fabrication, electric vehicle battery production, and advanced materials processing have reported a demand for skilled labor. However, this growth is not uniform. Some traditional manufacturing sectors, facing automation pressures or struggling with higher input costs from tariffs, have seen slower job growth or even minor contractions. The challenge remains in matching the skills of the available workforce with the demands of modern, high-tech manufacturing jobs, indicating a need for continued investment in workforce development and training programs to fully capitalize on potential job gains.
Capital Investment and R&D Spending
One of the most promising indicators in Q1 2026 has been the trend in capital investment and research and development (R&D) spending by domestic manufacturers. The various tax incentives and subsidies aimed at encouraging US-based investment appear to be yielding results. Several major corporations have announced plans for new factory constructions or significant upgrades to existing facilities, particularly in strategic sectors like clean energy technologies and advanced electronics. This suggests a long-term commitment to increasing domestic production capacity and technological leadership. R&D spending has also seen an increase, driven by government grants and the perceived need to innovate to maintain competitiveness in a more protected, but also potentially more expensive, domestic market. This investment in physical capital and intellectual property is crucial for the sustained growth and global competitiveness of US manufacturing.
Sector-Specific Impacts: Winners and Watch-List Industries
The impact of the new US trade policies in Q1 2026 has been highly sector-specific. Winners emerging in this early phase include:
- Semiconductors: With significant government investment and a focus on supply chain resilience, domestic semiconductor manufacturing is experiencing a boom, attracting substantial capital and job growth.
- Electric Vehicles & Batteries: Policies promoting clean energy and domestic EV production have spurred investment in battery gigafactories and EV assembly plants across the US.
- Basic Metals (Steel, Aluminum): Targeted tariffs have provided a shield against cheaper imports, leading to increased domestic demand and production for these foundational industries.
Watch-list industries, facing more complex challenges or slower adaptation, include:
- Apparel and Textiles: While some ‘Made in USA’ initiatives exist, the sector still struggles with high labor costs compared to international competitors, and tariffs on raw materials can increase production expenses.
- Consumer Electronics Assembly: Many US companies rely on global supply chains for components, and disruptions or higher costs for these parts can squeeze margins, making domestic assembly less competitive without significant automation.
- Specialized Chemicals: While some segments benefit, the highly integrated global nature of the chemical industry means that tariffs on specific inputs can create bottlenecks or increase costs for downstream domestic manufacturers.
These initial trends underscore that while the overall direction of the new trade policies is towards strengthening US manufacturing, the journey is complex and uneven, requiring continuous monitoring and adaptive strategies from both policymakers and industry leaders.
Challenges and Opportunities for Domestic Manufacturers
The implementation of new US trade policies in Q1 2026 has created a dynamic environment for domestic manufacturers, presenting both significant challenges that demand strategic navigation and substantial opportunities that, if seized, could reshape the future of American industry.
Navigating Supply Chain Disruptions and Cost Increases
One of the most immediate and pervasive challenges for many US manufacturers is adapting to changes in global supply chains. Policies aimed at de-risking and reshoring, while beneficial in the long term, can cause short-term disruptions. Companies that have historically relied on a global network of suppliers, particularly from countries now subject to higher tariffs or stricter import regulations, are facing increased costs for raw materials and components. This necessitates a re-evaluation of existing supplier relationships, often involving a search for new domestic or ‘friend-shored’ alternatives. The process of qualifying new suppliers, negotiating contracts, and establishing new logistical pathways can be time-consuming and expensive. For some manufacturers, these increased input costs may need to be absorbed, impacting profit margins, or passed on to consumers, potentially affecting competitiveness. The emphasis on supply chain resilience also means that manufacturers must invest in greater visibility and agility within their networks, which can be a significant operational and financial undertaking.
Workforce Development and Skill Gaps
While the new policies aim to create more manufacturing jobs, a persistent challenge is the availability of a skilled workforce. Modern manufacturing, particularly in high-tech sectors like semiconductors, advanced robotics, and clean energy, requires specialized skills that are not always readily available in the existing labor pool. There’s a growing skill gap between the demands of advanced manufacturing and the current capabilities of the workforce. Domestic manufacturers are finding it challenging to recruit and retain talent for roles requiring expertise in automation, data analytics, advanced materials science, and digital fabrication. This necessitates increased investment in workforce development and training programs, apprenticeships, and collaborations with educational institutions. Without a robust strategy to address this skill gap, the full potential of reshoring and domestic production incentives may not be realized, hindering the growth of the US manufacturing base.
Opportunities in Reshoring and Nearshoring
Despite the challenges, the new trade policies present significant opportunities for domestic manufacturers, particularly through the trends of reshoring and nearshoring. Government incentives, coupled with a desire for greater supply chain control and reduced geopolitical risk, are encouraging companies to bring production facilities back to the United States or to nearby countries. This creates a surge in demand for manufacturing infrastructure, equipment, and services within the US. Companies that can demonstrate robust domestic capabilities and competitive advantages in areas like automation, quality control, and sustainable production are well-positioned to benefit from these trends. Reshoring not only creates jobs but also fosters a virtuous cycle of innovation, as manufacturers invest in advanced technologies and processes to remain competitive in a higher-cost environment. This is a chance for American industry to modernize and reassert its leadership in key global sectors.
Technological Adoption and Innovation
The push for domestic manufacturing is closely linked with an imperative for technological adoption and innovation. To compete effectively in a global market, even with some protectionist measures, US manufacturers must embrace Industry 4.0 technologies such as artificial intelligence, robotics, additive manufacturing, and the Internet of Things (IoT). The new trade policies, through R&D subsidies and investment incentives, are indirectly encouraging this technological leap. Domestic manufacturers have an opportunity to become leaders in smart manufacturing, creating highly efficient, flexible, and sustainable production processes. This not only improves competitiveness but also creates higher-value jobs and strengthens the US’s position as a global innovation hub. Companies that proactively invest in these technologies will be better equipped to manage supply chain complexities, optimize production, and respond rapidly to market changes, turning policy-driven shifts into long-term strategic advantages.
Market Access and Export Potential
While some policies focus on domestic protection, others aim to open new markets for US exports through strategic trade agreements. For manufacturers, this presents an opportunity to expand their customer base beyond domestic borders. By ensuring fair competition and reducing trade barriers in key international markets, these agreements can provide US-made goods with greater access and competitive pricing. However, manufacturers must also be agile enough to meet diverse international standards and consumer preferences. The focus on ‘friend-shoring’ also means that US manufacturers might find it easier to integrate into supply chains with allied nations, creating more robust and politically stable export pathways. This dual approach of domestic strength and strategic international engagement can unlock new avenues for growth and diversification for American manufacturers.
Long-Term Implications and Future Outlook
The initial observations from Q1 2026 regarding the new US trade policies and their impact on domestic manufacturing provide a snapshot, but the true test lies in their long-term implications. The trajectory set by these policies suggests a fundamental shift in the US approach to global trade and industrial strategy, with far-reaching consequences for the nation’s economic structure, international relations, and global competitiveness.
Reshaping the US Industrial Base
The most significant long-term implication is the potential for a substantial reshaping of the US industrial base. The concerted effort to reshore critical manufacturing, coupled with incentives for strategic industries, is designed to create a more resilient, diversified, and technologically advanced domestic production capacity. This could lead to a revitalization of industrial towns and regions, fostering new ecosystems of suppliers, innovators, and skilled labor. Over time, a stronger domestic manufacturing base could reduce the US’s vulnerability to global supply chain shocks, geopolitical tensions, and economic coercion. However, this transformation will require sustained policy commitment, significant public and private investment, and continuous adaptation to global technological and market changes. The success will be measured not just in output, but in the creation of high-wage, sustainable jobs and the enhancement of national security through self-sufficiency in key sectors.
Impact on Global Trade Relations and Alliances
The US’s inward-looking trade policies, even when framed as strategic reshoring, inevitably have ripple effects on global trade relations. While the emphasis on ‘friend-shoring’ aims to strengthen ties with allies, other nations, particularly those previously central to US supply chains, may view these policies as protectionist. This could lead to retaliatory measures, new trade blocs, or a fragmentation of the global trading system. The long-term challenge for the US will be to balance its domestic industrial policy with its role as a leader in the global economy, ensuring that its actions do not inadvertently undermine the very international cooperation needed to address shared challenges. The success of these policies will partly depend on the US’s ability to articulate a clear and consistent trade narrative that reassures allies while strategically confronting perceived unfair practices from competitors.
Inflationary Pressures and Consumer Costs
A critical long-term consideration is the potential for sustained inflationary pressures and increased consumer costs. While domestic production can offer advantages in terms of quality and reliability, it often comes at a higher labor and regulatory cost compared to manufacturing in other countries. If tariffs remain high and reshoring efforts lead to higher production expenses, these costs may eventually be passed on to consumers. The challenge for policymakers will be to manage this trade-off, ensuring that the benefits of a stronger domestic industrial base outweigh the potential for increased prices for everyday goods. Innovation, automation, and economies of scale in newly established domestic industries will be key to mitigating these inflationary pressures over time. The Q1 2026 data offers early signals, but the full impact on consumer purchasing power will only become clear over several quarters.
Technological Leadership and Innovation Ecosystem
The new trade policies are explicitly designed to foster technological leadership and strengthen the US innovation ecosystem. By directing investment and R&D towards critical technologies, the US aims to maintain its competitive edge in areas like AI, biotechnology, advanced materials, and clean energy. In the long run, this could lead to a more dynamic and innovative manufacturing sector, capable of producing high-value goods and services. The creation of regional innovation hubs, supported by federal funding and private sector collaboration, could become a hallmark of this new industrial strategy. The success of this vision hinges on sustained investment in education, research, and infrastructure, ensuring that the US remains a magnet for talent and a birthplace for groundbreaking technologies that power the next generation of manufacturing.
Adaptability and Resilience in a Volatile World
Ultimately, the long-term success of these US trade policies will be judged by their ability to enhance the adaptability and resilience of domestic manufacturing in an increasingly volatile global environment. The goal is to build an industrial base that can withstand future economic shocks, geopolitical disruptions, and technological shifts. This means fostering manufacturing processes that are agile, sustainable, and less dependent on single points of failure. The Q1 2026 analysis indicates that while the path is complex, the foundational elements for a more robust and self-reliant manufacturing sector are being put into place. The coming years will reveal whether these strategic shifts can truly future-proof American industry and secure its prosperity in the 21st century.
Conclusion
The first quarter of 2026 has provided a vital initial assessment of the new US trade policies and their multifaceted impact on domestic manufacturing. It is clear that these policies represent a significant strategic pivot, aiming to bolster national economic security, stimulate job growth, and enhance supply chain resilience through a combination of targeted tariffs, robust incentives for domestic production, and a re-evaluation of international trade agreements. The analysis reveals a complex landscape where some sectors are experiencing immediate benefits and increased investment, while others grapple with rising input costs and the challenges of adapting global supply chains.
Initial economic indicators point to a gradual increase in manufacturing output and employment in strategic sectors, alongside a promising uptick in capital investment and R&D spending. This suggests that the foundational elements for a revitalized industrial base are being laid. However, the journey is not without its hurdles. Domestic manufacturers must contend with potential supply chain disruptions, the critical need for a skilled workforce to meet the demands of advanced manufacturing, and the delicate balance between protecting domestic industries and maintaining global competitiveness.
Looking ahead, the long-term implications of these policies could reshape the very fabric of the US industrial landscape, fostering a more self-reliant and technologically advanced manufacturing sector. This transformation, however, requires sustained commitment from policymakers, continuous adaptation from businesses, and ongoing investment in innovation and workforce development. The success of this ambitious undertaking will ultimately be measured by its ability to create sustainable economic growth, high-quality jobs, and a more resilient American economy capable of navigating the complexities of the 21st-century global environment. The Q1 2026 data serves as a crucial starting point for understanding this evolving narrative, underscoring the dynamic interplay between policy, industry, and global economic forces in shaping the future of US manufacturing.